cropper

Concierge Tax VIP

  • Home
  • Home
  • Menu
    • tax strategies for businesses
    • Business growth consultation
    • Fractional CFO for business growth
    • Growth Strategies
  • All Posts
  • Growth Strategies
  • Fractional CFO for business growth
  • tax strategies for businesses
  • Business growth consultation
March 18.2026
1 Minute Read

Discover High-Income Tax Strategies to Maximize Savings

Did you know that roughly 60% of high-income earners overpay by thousands each year due to overlooked tax strategies? Navigating the complexities of high-income tax strategies can determine whether you grow or lose hard-earned wealth. This comprehensive guide will show you how smart planning can put more money back in your pocket and secure lifelong finances, even as regulations and brackets change.

A Startling Truth: Why High-Income Tax Strategies Matter More Than Ever

For high-income earners, tax planning isn't just about reducing a bill—it's a powerful tool for building long-term wealth. The stakes are higher today with evolving federal and state tax laws, bracket shifts, and new limits on deductions. If you make over $200,000, you’re at much greater risk of entering higher tax brackets, facing the dreaded “60% trap,” and missing out on substantial tax deductions and credits. With record numbers of affluent households in the U. S. and a changing tax landscape, personalized high-income tax strategies are no longer optional—they’re essential for financial success.

Failing to implement an optimized tax plan can result in unnecessary losses—not just from paying more in income tax, but also from missing out on opportunities like capital gains harvesting, pre-tax contributions, and state tax minimization. Today’s high earners face an increasingly complex web of regulations, making proactive, regular reviews and adjustments more critical than ever to secure and grow your wealth.

The Impact of Tax Planning for Income Earners: Recent Statistics and Trends

According to recent studies, high-income households that engage in year-round tax planning reduce their effective tax rates by an average of 5–8% annually compared to those who only address taxes at year-end. With the IRS reporting more audits and new thresholds for capital gains, advanced planning isn’t just a bonus—it’s a necessity. High earners also face tighter limits on popular deductions, underscoring the importance of timely decisions about when to harvest losses, maximize savings accounts, and leverage real estate for deductions. The message is clear: Informed tax strategies can unlock significant long-term gains and shield your income from costly errors.
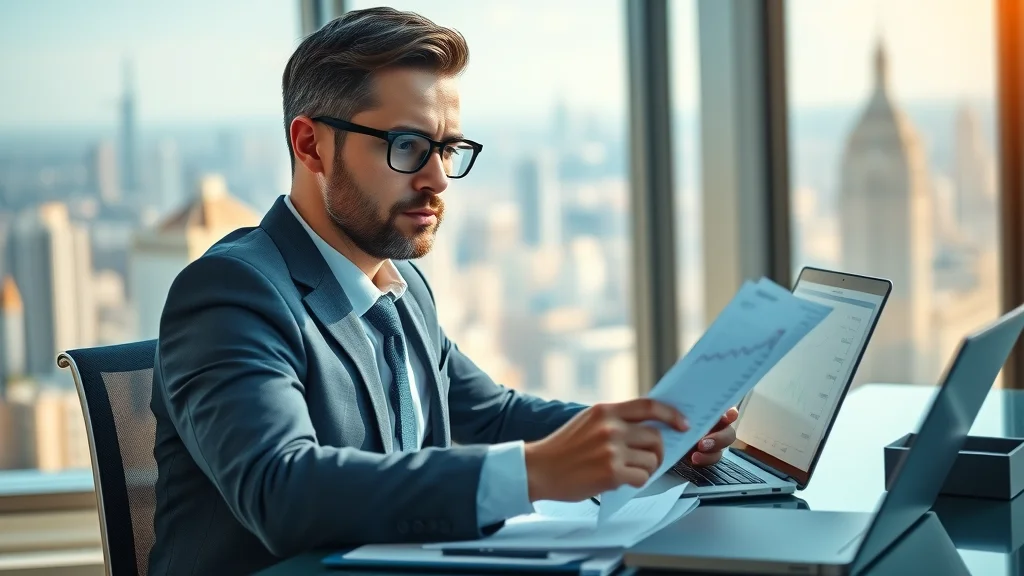
Modern professional financial advisor reviewing investment documents related to high-income tax strategies, photorealistic office with paperwork and laptop, crisp textures, sunlit background, city view.

How Smart Tax Plan Choices Can Drastically Affect Your Wealth

A well-designed tax plan does more than lower your tax bill; it actively boosts your portfolio and cash flow. By targeting pivotal areas—like loss harvesting, optimal timing for capital gains recognition, and strategic use of retirement accounts—income earners can significantly increase their net worth over time. Take the example of shifting investments to harvest taxable losses or relocating to minimize state tax; these decisions alone can save thousands annually. Layer in proactive reviews with a tax advisor, and a smart tax plan quickly becomes a cornerstone of lasting wealth.

The right choices impact your life not just in April, but year-round: from maximizing employer retirement contributions and leveraging HSAs, to choosing between a Roth IRA and a Traditional IRA. When coordinated with deductions, credits, and specialized planning strategies, these tactics can be transformative—for both annual savings and multi-decade financial security.

What You'll Learn from This Complete Guide to High-Income Tax Strategies

  • An overview of key tax planning concepts
  • How to make practical tax-saving decisions
  • Planning strategies unique to high-income earners
  • The effect of investment choices on income tax
  • Maximizing deductions and credits
  • Avoiding costly tax mistakes

Clean infographic showing key concepts for high-income tax planning and strategies for income earners, digital diagrams, modern workspace, photorealistic, green and navy color scheme.

Understanding High-Income Tax Strategies: A Comprehensive Introduction

Who Should Consider Advanced Tax Planning?

Advanced tax planning is particularly crucial for individuals whose annual income exceeds the top 10% thresholds—typically those earning more than $200,000. This includes top-earning professionals, executives, business owners, real estate investors, and those with multiple sources of income or substantial investment portfolios. If your taxable income regularly pushes you into the 32% or 37% federal tax bracket, or if you struggle with unpredictable income spikes from bonuses, commissions, or stock options, advanced planning strategies are essential. Even high-earning freelancers and consultants can benefit tremendously from understanding how deductions, credits, and proactive contributions combine to reduce year-end liabilities.

The more complex your financial plan becomes—with multiple properties, business interests, or cross-state income—the more vital it is to move beyond basic tax preparation into strategic, forward-looking planning. Engaging a seasoned tax advisor who understands high-income nuance can spotlight savings opportunities that mainstream filers simply miss.
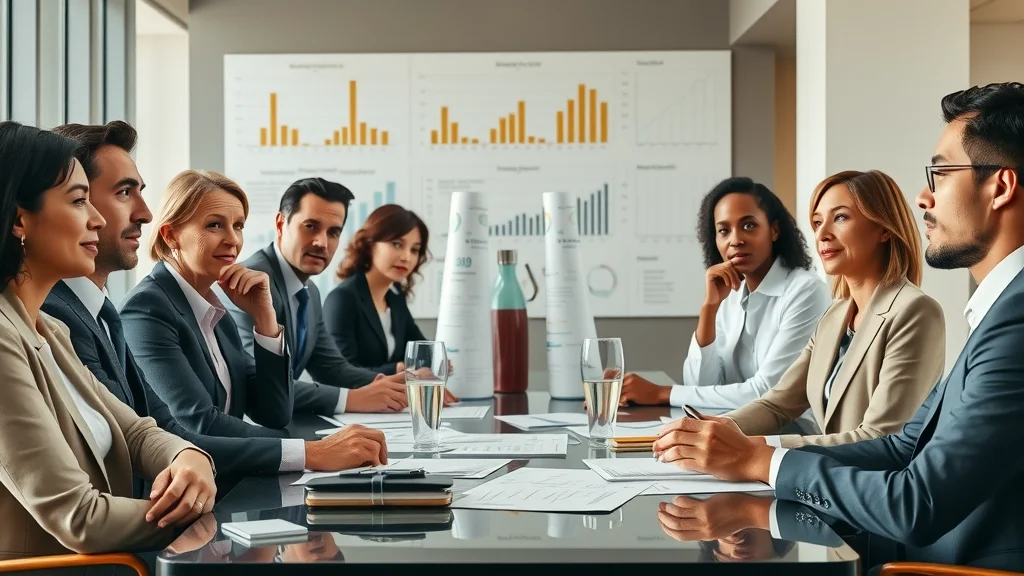
Diverse group of affluent professionals discussing advanced high-income tax strategies at a conference table, executive meeting room, financial diagrams in background, realistic gold and neutral tones.

How Taxable Income Influences Your Tax Plan

Your total taxable income is the foundation of your tax plan. As your income rises, you're exposed not only to higher ordinary income tax brackets but also to phased-out credits, the Net Investment Income Tax, and reduced eligibility for some deductions. High-income earners must be laser-focused on how every financial decision—bonuses, investment returns, business profits—affects taxable income and place in the tax code hierarchy. Specialized planning strategies are needed to avoid unintentional jumps in effective tax rate and maximize legal deductions.

For instance, timely moves—such as using pre-tax retirement or savings accounts, bunching deductions, or realizing losses in underperforming investments—can help smooth out spikes in taxable income. Understanding and forecasting how lifestyle or investment changes affect your tax profile will position you to minimize what you owe and build a more resilient financial plan.

Annual Income Earners: Key Planning Strategies

For annual high-income earners, thoughtful planning strategies can deliver powerful tax-saving results. This means looking at both the cumulative impact of investment income, bonuses, and stock sales, as well as one-off windfalls. Aggressively contributing to retirement and savings accounts (like 401(k)s and IRAs), leveraging investment losses (particularly toward year-end), managing the timing of capital asset sales, and structuring real estate investments for depreciation are all proven tactics. The most effective plans employ a year-round approach—reviewing income patterns, optimizing deductions, and adjusting allocations as soon as new information arises.

“A well-executed tax plan is one of the most powerful wealth-building tools for high-income earners.” — Leading Tax Advisor

Essential Tax Planning Strategies for High-Income Earners

Income Tax Bracket Navigation and Reduction Techniques

  • Understanding the 32% and 37% tax brackets
  • Loss harvesting and capital gains optimization
  • The risk of the 60% trap

Navigating the upper tax brackets is a core concern for high-income households. Exceeding the 32% or 37% bracket often means losing out on deductions, being hit by the Net Investment Income Tax, and facing phaseouts for popular credits. Strategic tax planning helps you “smooth” your income—harvesting losses during peak years, offsetting gains with underperforming assets, and maximizing pre-tax contributions. Mastery of these tactics reduces spikes in your annual tax bill and shields more of your income from upper-tier rates.

Additionally, awareness of the "60% trap"—situations where stacking deductions can tip you into a punitive effective rate—is vital to avoid costly surprises. By intentionally managing salary increases, bonuses, and investment sales in the context of your overall tax plan, you ensure that every dollar you earn works harder.
Hands holding a tax bracket chart and calculator, financial documents spread out, high-income tax planning with green home office decor and coffee in the background, realistic textures.

Tax Deduction Optimization for Income Earners

Maximizing available tax deductions is central to effective high-income tax strategies. Be on the lookout for hidden or often-overlooked deductions: charitable contributions, mortgage interest (particularly on larger principal amounts), large state and local taxes (when deductible), retirement account and HSA contributions, and investment losses. Strategically bunching charitable donations into a single tax year, leveraging donor-advised funds, or pre-paying property taxes are all methods to stack deductions above the standard level in high-income years.

Closely assessing your itemized deductions against annual thresholds can help reduce your taxable income and move you into a more favorable bracket. Work with a tax advisor to ensure you’re not leaving potential deductions unclaimed or risking audit triggers through poor documentation or aggressive assumptions.

State Tax Minimization Approaches

Many high-income earners in high-tax states can lose up to 10% of their adjusted gross income just to state and local taxes. If possible, evaluate residency and domicile options—relocating to a no-income-tax state can result in six-figure savings over a decade. For those unable to move, look to maximize use of deductions still allowed under SALT limitations, track work performed out of state, or utilize business structures (like S corporations) to selectively allocate income.

Some also reduce state tax through investment in municipal bonds or other vehicles exempt at the state level. Coordinating with a local tax professional knowledgeable in both state and local tax nuances can help you stay legally compliant while dramatically reducing your overall exposure.

The Importance of Regular Tax Plan Reviews

Your tax plan is not a set-it-and-forget-it document. Life changes—job changes, investment shifts, new business interests, or moving between states—demand regular reviews. Annual and mid-year tax “check-ups” ensure your planning strategies are updated and risks are mitigated. Income earners who work with advisors to stay up to date on regulations, deduction limits, and new savings opportunities consistently outperform those who delay until tax season.

Long-term success comes from adapting as your income, assets, and liabilities evolve. Quick reactions to legislative changes or unusual income years can save thousands, preserve wealth, and ensure ongoing compliance with ever-changing tax laws.

Advanced Investment and Asset Planning Strategies
Professional investor overlooking luxury urban real estate buildings, reviewing portfolio, city skyline at sunset, photorealistic penthouse balcony, warm golden hour light.

Leveraging Real Estate for Tax Advantages

Real estate remains one of the most effective vehicles for high-income tax reduction. From depreciation allowances to 1031 exchanges, real property investment can dramatically reduce current taxable income and defer capital gains. Savvy investors structure ownership for maximum benefit—using cost segregation to accelerate depreciation or investing in opportunity zones for deferred gains. For those who also own rental properties, proper deductions for mortgage interest, repairs, and property taxes can stack up quickly, turning potential liabilities into cash-flowing assets.

Consult a tax advisor experienced in real estate to ensure your financial plan leverages every possible deduction and keeps you on the right side of IRS compliance.

Capital Gains and Capital Gain Harvesting Explained

Understanding the mechanics of capital gains taxes is essential for high-income earners. Gains from the sale of stocks, mutual funds, or real property can push your taxable income into higher brackets and trigger additional federal or state tax liabilities. Strategic capital gain harvesting—timing sales to fall into lower-tax years, or offsetting gains with harvested investment losses—can dramatically lower your overall tax bill.

High earners should plan asset sales with the tax implications front and center, taking into account holding periods, state residency, and expected income spikes. Thoughtful harvesting can also be coordinated with charitable giving to “wipe out” the liability on appreciated assets donated to qualified organizations.

The Role of Loss Harvesting in Year-End Tax Planning

Loss harvesting is a powerful end-of-year strategy for high-income earners. This approach involves selling securities that have declined in value to offset taxable gains elsewhere in your portfolio. The resulting losses can be used to lower your present taxable income and, in some cases, carried forward to mitigate future gains.

Consistent, disciplined loss harvesting deflects spikes in income tax and enables a flexible, resilient investment strategy. Partner with a tax professional or financial planner to automate reviews and ensure all opportunities are captured—especially as volatility creates new potential losses and gains.

"Investing wisely isn’t just about returns—real estate and loss harvesting can be game-changers for high-income tax strategies." — Certified Public Accountant

Retirement and Savings for High-Income Individuals

Maximizing Retirement Plan Contributions (401(k), IRA, Roth IRA, Traditional IRA)

Retirement plans remain a leading defense against rising tax bills. Each year, high-income earners should fully leverage 401(k) salary deferrals (up to $22,500 for 2023, plus catch-up if over 50) and make the maximum possible contributions to IRAs—even if Roth IRA income limits apply, backdoor Roth strategies may still be available.

Pre-tax contributions directly reduce your taxable income, lowering the effective bracket for the year. Meanwhile, after-tax Roth IRA and Roth 401(k) contributions may provide superior long-term value if you expect higher tax rates in future retirement years. Coordinating the right mix with your financial plan ensures you enjoy both short-term deductions and long-term tax-free growth.
Affluent couple planning retirement, reviewing 401(k) and IRA options, happy and relaxed at modern dining table, soft earth tones and gentle morning sunlight.

Comparing Roth IRA vs Traditional IRA Tax Impacts

Choosing between a Roth IRA and a Traditional IRA is a recurring dilemma for high-income earners. The key distinction: Traditional IRAs offer immediate tax deductions (lowering current taxable income), while Roth IRAs enable tax-free growth and withdrawals in retirement. Unfortunately, Roth IRA eligibility is phased out as income increases, but high earners may still access Roth advantages via the “backdoor” method—contributing after-tax to a Traditional IRA, then converting.

The optimal choice hinges on both current and expected future tax rates. High earners in peak earning years may prefer immediate savings, while those projecting higher future rates or inheriting large balances may benefit more from Roth accounts. Consulting a tax advisor can illuminate the most efficient path for your personal scenario.

Harnessing the Power of Health Savings Accounts (HSA) and Other Savings Accounts

For those eligible, health savings accounts (HSA) are among the only vehicles that provide a threefold benefit: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. Maximizing HSA contributions and investing the funds for long-term growth transforms routine healthcare savings into a powerful wealth strategy for high-income households.

Other savings vehicles, such as 529 plans for education or high-yield savings accounts, also play an important supplementary role. By coordinating HSA and other account contributions with your tax plan, you’re able to further limit taxable income and boost overall after-tax net worth.
Hand adding coin to HSA savings jar, stacked coins, high-income tax savings, photorealistic modern kitchen, daylight, secure financial planning mood.

Long-Term Financial Plan Alignment with Tax Strategies

It’s vital to remember that tax planning is integral—not incidental—to your overall financial plan. Far too often, high earners address taxes reactively instead of including them in annual and multi-decade projections. By thinking ahead—especially for major events like retirement, large asset sales, or moving between states—you proactively manage potential liability and maximize opportunity.

Most importantly, regular collaboration between your tax advisor and investment professionals ensures no part of your plan is working at cross-purposes. Together, you can balance tax savings now against future flexibility and security, making every dollar fulfill more than one objective.

Business Owners and Tax Strategies: Special Considerations

Tax Planning for Business Owner Income

If you’re a business owner, your tax landscape is more complex—and your opportunities more significant. Income may flow through as salary, dividend, or pass-through distributions, each carrying separate tax implications. Planning strategies include choosing the most tax-efficient entity structure, maximizing business deductions (such as home office, retirement, and health benefits), and timing profitability or capital expenditures.

Formalizing your tax plan annually and reviewing it quarterly can help identify areas to shift or defer income, accelerate deductible spending, or leverage available credits before they expire. Even something as simple as properly structuring a business vehicle purchase or leveraging Section 199A for qualified business income can create substantial savings.
Entrepreneur reviewing business tax planning options, intentional expression, home office with practical props and greenery, writing in notepad.

Pass-Through Vs Corporate Taxation: What High-Income Earners Need to Know

Understanding how pass-through vs corporate taxation affects your tax liabilities is vital for business-owning high-income earners. S corporations, partnerships, and LLCs pass income directly to the owner's personal return, often with eligibility for the 20% qualified business income deduction (Section 199A). In contrast, C corporations are subject to corporate tax rates and potential double-taxation on distributed dividends. Each structure impacts your effective tax rate, eligibility for deductions, and strategies for reinvestment or personal withdrawals.

Tailor your choice to your growth goals, profitability, and the balance of personal vs business tax liability. Frequent reviews, especially when laws or your bottom line shifts, ensure ongoing advantage.

Tax Plan Opportunities for Entrepreneurial Income

Entrepreneurs have access to unique tax plan advantages, such as accelerated depreciation under Section 179, R&D credits, retirement plan options for both owners and employees, and special deductions (home office, travel, and health insurance). Actively monitoring available incentives and structuring income payments can further lower both personal and business taxes.

Collaboration with a proactive tax advisor can lead to creative legal strategies—shifting income to lower-tax years, qualifying for additional credits, or expanding before legislative windows close.

Multi-State and International Tax Planning for High-Income Earners
Professional analyzing US map on dual computer screens, concentrated expression, checking multi-state tax strategies, modern tech-forward office, blue and green accents.

Navigating State Tax Challenges When Living or Working in Multiple States

Living or working across state lines brings a host of unique tax planning issues—and opportunities. High-income individuals increasingly work remotely, own property in multiple states, or split work between offices, all of which can impact residency status and tax liability. Knowing where you’re considered a “resident” and only paying state tax where owed can prevent double taxation and unintentional penalties.

Be sure to keep meticulous records of where you live and work, as residency audits are on the rise. State-to-state coordination may open up deductions for travel, temporary housing, or even enable income-shifting if your business is registered in a tax-advantaged state.

International Income and Tax Strategies

Global income adds another layer of complexity to the high-income tax plan, with risks of dual taxation and reporting requirements. Foreign earned income exclusions, tax treaties, credits for foreign taxes paid, and strategic use of offshore investment vehicles are just a few levers available. Even U. S. -based income with international partners can require additional planning and documentation.

If your income crosses borders, seek specialized advisors who understand both domestic and foreign tax codes. The right high-income tax strategies help keep your world-wide wealth compliant and efficiently taxed.

The Role of a Professional Tax Advisor in High-Income Tax Strategies
Distinguished tax advisor consulting with high-income client, engaged discussion, wooden desk with tax law books, soft warm lighting, attentive posture.

How to Choose an Expert Tax Advisor

Selecting a tax advisor with specific experience serving high-income households is critical. Look for credentials (CPA, EA, or tax attorney), years of experience with seven-figure earners or complex business/investment structures, and proactive communication style. A great advisor should offer personalized recommendations based on your entire financial plan—not just fill out forms.

Ask for references and be clear about your planning priorities: Are you focused on minimizing current year tax, preparing for a liquidity event, or building generational wealth? Your advisor should be ready to design strategies tailored to your unique needs.

When to Consult a Tax Advisor for Income Tax and Taxable Income Optimization

Don’t just call your advisor in April—proactive, year-round engagement delivers the best results. Consult when there are major changes (job jump, marriage, sale of investment or business), at the start of every year, and for regular “mid-year checkups. ” High-income earners should especially seek guidance before making large financial moves to ensure they optimize taxable income and avoid costly surprises.

Having an industry expert on call keeps you ahead of deadlines, alert to new opportunities, and insulated from pitfalls unique to high earners.

Major Red Flags and Common Mistakes Even Seasoned Income Earners Make

Common mistakes include passively accepting last year’s assumptions, ignoring new deduction limits, failing to document residency, or missing out on timing opportunities for deductions or capital gains. Rushed year-end decisions, “set it and forget it” retirement contributions, or underutilizing business incentives can add up to tens of thousands in avoidable taxes.

Proactive, customized reviews are the best defense against inadvertently leaving money on the table.

Comparison of High-Income Tax Strategies: Deductions, Credits, and Potential Savings
Strategy Type (Deduction/Credit) Potential Annual Savings Who Benefits Most?
Max 401(k), IRA Contributions Deduction $5,000–$11,000 All high-income earners
Loss Harvesting Deduction Up to $3,000/year (+offset gains) Investors, Real Estate Owners
Charitable Giving Deduction Varies (often $10,000+) Philanthropically inclined, business owners
HSA Contribution Deduction $3,850–$7,750 Individuals with high-deductible healthcare
Qualified Business Income (Sec 199A) Deduction Up to 20% of QBI Business Owners
Roth Conversion (Strategic Years) Credit/Exclusion Long-term tax-free growth High earners planning for retirement
Relocate for State Tax Savings Credit/Exclusion $10,000–$50,000+ High earners in high-tax states

Case Studies: Successful High-Income Tax Strategies in Action

  • A tech executive maximizing capital gains harvesting
  • A business owner reducing state tax through relocation
  • Real estate investor utilizing loss harvesting

Each case highlights the multiplicative effect of proactive tax strategy. The tech executive times option sales with loss harvesting, reducing their effective tax rate by 7% and saving over $30,000. The business owner’s relocation trims annual state liability nearly in half, unlocking capital for investment. The real estate investor, meanwhile, leverages annual depreciation and property upgrades to offset gains—even rolling profits into new investments tax-free through a 1031 exchange.

These real-world examples prove that high-income tax planning is not just for the ultra-wealthy—any income earner prepared to take action can see transformative benefits.

Expert Quotes: Insights from Leading Tax Professionals on High-Income Tax Strategies

“Personalization is everything—a customized tax plan for high-income earners is the foundation of modern wealth management.” — Tax Planning Specialist

Top professionals agree: there’s no one-size-fits-all formula. Success lies in tailoring each aspect of your plan—deductions, investments, legal entity choices—to your unique lifestyle, family, and business goals.

Lists of Common High-Income Tax Deductions and Credits

  • Charitable contributions
  • Mortgage interest
  • Retirement account contributions
  • Health savings account deposits
  • Investment loss deductions

People Also Ask: Answers to Key Questions About High-Income Tax Strategies

What are some tax strategies for high-income earners?

Comprehensive Answer: High-income tax strategies include loss harvesting, maximizing retirement and savings account contributions, real estate investments, capital gains harvesting, strategic charitable giving, and utilizing professional tax advisors for customized tax plans.

Can I give my kids $100,000 tax free?

Comprehensive Answer: While the IRS sets an annual gift exclusion limit ($17,000 per recipient in 2023), larger amounts may require filing a gift tax return but often do not result in immediate taxes due to the lifetime exemption. Review annual regulations with a tax advisor.

How to avoid 32% tax bracket?

Comprehensive Answer: High-income earners can avoid or minimize entering higher tax brackets through advanced planning strategies—maximizing pre-tax contributions, using loss harvesting, scheduling capital gains, and utilizing certain deductions.

What is the 60% trap?

Comprehensive Answer: In tax planning, the '60% trap' can refer to scenarios where stacked deductions overcome income limits, leading to unanticipated high effective rates. Proactive tax plan reviews can help avoid the trap.

High-Income Tax Strategies FAQs

  • What is the most overlooked tax deduction for high-income earners?
  • How does real estate investment impact taxable income?
  • When is loss harvesting most effective?
  • Are Roth IRAs always better for high-income earners?
  • How can high-income earners reduce state tax liabilities?

Watch this in-depth expert panel as leading financial planners and tax advisors break down high-income tax strategy essentials. Visual diagrams and engaging analysis reinforce why smart tax decisions can measurably boost your take-home income. Ideal for executives, entrepreneurs, and investors aiming for next-level financial security.

Discover how leveraging real estate and capital gains strategies can lower your tax bill and supercharge your net worth. Featuring success stories, actionable advice, and visual aids tailored to affluent individuals with growing property portfolios.

Key Takeaways: Mastering High-Income Tax Strategies for Lifelong Wealth

  • Proactive tax planning directly increases take-home income for high earners
  • Diversification of strategies (real estate, retirement plans, charitable giving) is essential
  • Regular consultation with a tax advisor ensures maximal savings
  • Being aware of state, federal, and capital gains nuances protects your wealth

Secure Your Wealth: Take the Next Step in High-Income Tax Planning

Give us a call @ 1.877.776.6829 or visit our website Conciergetax.vip today.

Conclusion: The Value of High-Income Tax Strategies For Every Income Earner

Establish a Tax Plan for Lifelong Financial Security

High-income tax strategies aren't just about lowering this year’s tax bill—they are foundational to building and preserving wealth for a lifetime. Make tax planning a central part of every financial decision you make.

Embrace Professional Guidance for Complex High-Income Scenarios

Partnering with a knowledgeable tax advisor keeps your finances future-ready, your savings maximized, and your wealth secure amid changing laws and life stages.

Sources:

  • https://www.irs.gov/taxtopics/tc409 – IRS High-Income Issues
  • https://www.kiplinger.com/taxes/601649/8-smart-tax-moves-for-high-income-earners – Kiplinger: Smart Tax Moves
  • https://www.investopedia.com/articles/tax/08/tax-strategies-high-income.asp – Investopedia: Tax Strategies
  • https://www.forbes.com/advisor/taxes/tax-strategies-high-income/ – Forbes: Tax Strategies for High Earners

To further enhance your understanding of high-income tax strategies, consider exploring the following resources: “How To Preserve Your Wealth: Tax Strategies For High-Income Earners” (forbes. com) This article outlines key methods for wealth preservation, including maximizing retirement contributions and utilizing Health Savings Accounts (HSAs) to reduce taxable income. “11 Ways for High Earners to Reduce Taxable Income [2026]” (blog. cmp. cpa) This resource provides a comprehensive list of strategies tailored for high-income individuals, such as prepaying property taxes and funding 529 plans for educational savings. By delving into these articles, you’ll gain actionable insights to effectively manage and minimize your tax liabilities.
tax strategies for businesses

18 Views

0 Comments

Write A Comment

*
*
Please complete the captcha to submit your comment.
Related Posts All Posts
10.02.2026

Struggling to Reduce Your Tax Liability? Here’s the Fix

Imagine opening your mailbox and seeing a smaller tax bill—no surprises, just a smoother tax year and the relief of knowing you’ve taken every step to reduce your tax liability. If you’ve ever felt uncertain about which tax moves really work or wondered if you’re missing savings, this guide provides clear, doable strategies. Read on to discover how a few smart tax tactics can mean less stress and more money in your pocket come tax season.Understanding How to Reduce Your Tax LiabilityReducing your tax liability doesn’t just trim your tax bill; it boosts your financial health year after year. By understanding the levers that affect your taxes—such as income, deductions, and credits—you gain control over how much you owe. Too many people think their tax bill is set in stone, but the reality is that with some straightforward tax planning, anyone can take action to pay less legally. Reducing your tax liability is crucial because it directly impacts your disposable income and future savings, especially as new tax law changes emerge each tax year.Common misconceptions keep people from lowering what they actually owe. Some believe that taxable income and the tax bill are the same, but that’s not the case. Your taxable income is what remains after all available deductions, while your tax bill is the final figure you owe after credits are applied. When you know the difference, you can leverage tactics like adjusting withholding, itemizing deductions, or contributing to tax-advantaged accounts, ensuring that your actual tax bill is as low as possible.Why reducing your tax liability is crucialCommon misconceptions about your tax bill and tax liabilityThe difference between your tax bill and taxable incomeWhat You’ll Learn About Reducing Your Tax LiabilityThis guide will empower you with practical knowledge to reduce your tax liability efficiently. You’ll discover essential strategies like maximizing tax credits, tax deductions, and contributing wisely to retirement accounts. These actionable tips are tailored not just for high earners, but for anyone looking to make their next tax year less burdensome and more strategic.We’ll break down how tax planning works in simple terms, clarify the role of tax credits and deductions, and explain how specific moves like loss harvesting or Health Savings Accounts can put dollars back in your pocket. Knowing what steps to take and when provides the foundation for a proactive approach, turning what often feels like a confusing process into a manageable and even empowering one.Effective strategies to reduce your tax liabilityHow tax planning, tax credits, and deductions factor inKey actionable tips tailored for various earnersThe Fundamentals of Tax Planning and Taxable IncomeTax planning means looking ahead throughout the year, not scrambling at the last minute. The key is to start early—review changes in tax law, evaluate your income, and map out your deductions and credits well before filing your return. Sound planning each tax year helps you lower your taxable income, which is the amount the IRS uses to calculate your federal tax bill.Understanding your gross income is step one, but knowing what counts as taxable income is where the real savings start. It’s not just about your salary, but also investment income, side hustles, and even interest from your savings account. Smart tax planning allows you to separate taxable from non-taxable sources and make strategic adjustments—like sheltering more funds in a retirement account or maximizing allowed deductions. Leveraging retirement accounts, particularly an IRA or 401(k), is a foundational way to reduce your taxable income and create long-lasting benefits for your tax year after tax year.Tax planning basics: Getting ahead each tax yearDistinguishing taxable income from gross incomeLeveraging retirement accounts for tax reductionTop Strategies to Reduce Your Tax LiabilityThere are several proven strategies that every taxpayer, regardless of income or filing status, can use to actively reduce their tax liability. These include understanding the power of tax credits and deductions, making the most of retirement account contributions, taking advantage of a health savings account, and even utilizing investment losses. Each approach works a bit differently, but with the right tax planning, most filers can see tangible results by the end of each tax year.It’s not about making risky moves—it’s about applying the rules of the tax code to your advantage. Whether you’re self-employed, earning a steady paycheck, or managing multiple income streams, smart choices now can cut your tax bill later. Below, we dig into the most effective tactics, with practical examples so you can confidently put them to work.Leverage Tax Credits and Tax DeductionsUnderstanding the difference between tax credits and tax deductions is critical in reducing your tax bill. A tax deduction lowers your taxable income, which in turn reduces the amount of income subject to federal tax. Itemizing deductions—such as mortgage interest, charitable contributions, or state and local tax payments—only makes sense if the total exceeds the standard deduction for your filing status.Tax credits, on the other hand, directly reduce the amount of tax you owe, dollar for dollar. Some of the most common credits include the Earned Income Tax Credit (EITC), Child Tax Credit, and education credits. These credits are incredibly valuable because they apply after your taxable income, making them one of the most effective methods to reduce your tax liability. Review your eligibility for each to ensure you don’t leave money on the table.Difference between tax credits and tax deductionsAvailable tax credits: What are you eligible for?Common tax deductions to considerUtilize Retirement Accounts: IRA Contribution and Traditional IRARetirement accounts, particularly IRAs and 401(k)s, play a major role in reducing your tax liability. Making an IRA contribution could lower your taxable income for the current year. For example, a traditional IRA allows eligible contributions to be deducted from your adjusted gross income, making immediate tax savings possible. Understanding your contribution limit is essential to avoid penalties and to maximize deductions.If you’re planning for long-term financial security, integrating traditional IRA contributions into your annual tax planning is wise. This strategy not only reduces your present-year tax bill, but also helps secure your retirement. Keep in mind that Roth IRA contributions do not yield current-year deductions, but traditional IRA contributions do—making them particularly useful for those seeking to lower this year’s taxable income.Maximizing IRA contribution benefitsTraditional IRA strategies to minimize taxable incomeWhy retirement account planning matters for your tax billBenefit from Health Savings Account (HSA) and Savings Account PlanningA Health Savings Account (HSA) is a triple-tax-advantaged tool for those with eligible health plans. Contributions to an HSA are tax-deductible, growth is tax-free, and qualified withdrawals are not taxed at all—making this one of the most effective ways to reduce your tax liability while managing healthcare costs. Annual contribution limits apply and are adjusted for inflation, so always check the latest IRS thresholds each tax year.Even something as simple as interest from a traditional savings account can have tax implications, as earned interest counts toward taxable income. While you may not be able to deduct savings account contributions, integrating an HSA into your overall savings and tax planning can produce significant benefits. Track your account balances and make contributions before the tax deadline to maximize your savings and minimize your tax bill.How a health savings account can reduce your tax liabilitySavings account interest and its tax implicationsTax advantages of using HSA and optimizing savingsCapitalize on Loss Harvesting to Offset Capital GainsCapital gains taxes can take a bite out of your investment returns, but loss harvesting offers a strategic solution. This involves selling securities at a loss to offset taxable capital gains elsewhere in your portfolio. The goal is to minimize your overall tax bill, not simply trade for the sake of it. Implementing loss harvesting means strategically timing trades and keeping detailed records for accurate reporting when you file.Effective loss harvesting does require an understanding of both tax rules and investment performance. Be mindful of the “wash sale” rule, which prohibits claiming a deduction if you repurchase the same asset within 30 days. Regular portfolio reviews, preferably before the end of each tax year, allow you to identify loss-harvesting opportunities. This proactive approach works especially well for investors managing non-retirement brokerage accounts.Understanding capital gains and loss harvestingApplying loss harvesting techniques effectivelyTips for implementing loss harvesting in your portfolioEssential Tax Planning Tips for Every Tax YearSuccessful tax planning relies on consistent, year-round effort—not just scrambling during tax season. Start by organizing your financial documents: keep receipts, IRS letters, and statements in a well-labeled file or digital folder. This makes itemized deductions, health savings accounts, and IRA contributions much easier to track and claim.Plan ahead for the next tax bill by anticipating major life changes—such as marriage, new dependents, or a job switch—that can affect your tax bracket or eligibility for tax credits. Keeping up with new tax law changes and available credits protects you from overlooking meaningful savings. Regular check-ins, even every quarter, mean fewer surprises and smoother filing when deadlines come around.Organizing your documents each tax yearPlanning for the next tax bill earlyStaying informed about new tax breaks and creditsExpert Advice on How to Reduce Your Tax Liability"Smart tax planning doesn’t have to be complicated. Start early, take advantage of available credits and deductions, and make the most of registered accounts." — Financial AdvisorProfessional tax advisors play a pivotal role in minimizing your tax bill. Whether you’re unsure about intricate deduction rules, eligibility for specific tax credits, or maximizing retirement account contributions, their guidance can pinpoint opportunities you might miss alone. A dedicated tax professional helps you avoid missteps such as misreporting or neglecting valuable breaks due to uncertainty.Consistency is key in tax planning. Review your tax situation on an annual basis—as laws and your finances change each year. This practice ensures optimal use of credits and deductions and helps you adjust strategies if you move to a new tax bracket or experience other significant changes. Avoiding pitfalls and getting expert input allows you to confidently reduce your tax liability, year after year.Why professional guidance can help you reduce your tax liabilityCommon pitfalls individuals face with tax credits and deductionsConsistency is key: Review your tax situation annuallyTable: Tax Credits, Deductions, and Accounts to Reduce Your Tax LiabilityMethodBenefit TypeWho Should UseTax CreditDirect ReductionAll TaxpayersTax DeductionIndirect ReductionItemizersIRA ContributionTax DeferralRetirement SaversHealth Savings Account (HSA)Tax-Free GrowthEligible Account HoldersLoss HarvestingOffset GainsInvestorsPopular Questions: Reduce Your Tax Liability (People Also Ask)How to legally reduce your tax liability?You can legally reduce your tax liability by maximizing eligible tax credits and deductions, contributing to retirement accounts like a traditional IRA or 401(k), and practicing smart tax planning year-round. Loss harvesting is also a valuable strategy, especially for those with investment income. Always keep current on the latest tax rules to ensure full compliance and optimal savings.Who gets the new $6000 tax break?The new $6000 tax break is associated with qualified traditional IRA contributions but eligibility depends on your income, filing status, and current tax law. Check with the IRS or a reliable tax professional to confirm if this break applies to you for the current tax year, and to ensure all requirements are met for claiming it on your tax return.How to reduce tax liability as a high earner?High earners can reduce tax liability by maximizing contributions to retirement accounts, utilizing a health savings account if eligible, and exploring advanced investment strategies such as loss harvesting to offset capital gains. They should also track eligible expenses closely for deductions and regularly review tax brackets, credits, and other opportunities with a trusted tax advisor.What is the $600 rule?The $600 rule requires reporting of certain online payments—such as those through third-party apps—which will be reported to the IRS for amounts over $600 annually. This rule means you’ll need to keep thorough records of such transactions for compliance, and review them for possible deductions or to determine your total taxable income.Answers: Expert Guidance on Reducing Your Tax LiabilityLegal strategies include maximizing credits and deductions, making eligible retirement account contributions, and strategic loss harvesting.The new $6000 tax break may apply to qualified traditional IRA contributions. Check IRS and tax law updates.High earners benefit from strategies like maximizing retirement contributions, health savings accounts, and sophisticated investment planning.The $600 rule refers to new IRS reporting for certain online payments—be sure to keep records for compliance and potential deductions.Video Resource: How to Reduce Your Tax Liability This YearVideo Resource: How to Reduce Your Tax Liability This YearVideo Resource: Tax Credits vs. Tax Deductions ExplainedVideo Resource: Tax Credits vs. Tax Deductions ExplainedList: Quick Tips to Reduce Your Tax LiabilityOrganize tax documents year-roundSet IRA and HSA contribution remindersTrack eligible expenses for deductionsKeep records for all sources of taxable incomeConsult a tax professional for annual reviewsFAQs: Reducing Your Tax LiabilityHow soon should I start tax planning to reduce my tax liability?The sooner you begin tax planning each tax year, the greater your opportunities to reduce your tax liability. Early preparation gives ample time to make deductible contributions, harvest losses, and identify credits.What’s the difference between tax credits and deductions when trying to reduce your tax liability?Tax deductions lower your taxable income, while tax credits reduce your actual tax bill directly—so credits generally offer greater savings.Can loss harvesting always reduce your capital gains tax bill?Loss harvesting can offset taxable capital gains, but its effectiveness depends on your specific investments and annual tax situation. It must be implemented carefully, following IRS rules.Are HSA contributions always tax-free?HSA contributions are typically tax-deductible and grow tax-free, but withdrawals must be for qualified medical expenses to retain that tax-free status.When should I consult a professional to help reduce my tax liability?If you have complex income, significant investments, or life changes (like marriage or inheritance), it’s wise to consult a tax professional each tax year for optimal savings and compliance.Key Takeaways for Reducing Your Tax LiabilityStart early with tax planning each tax yearUtilize accounts like IRA and HSAUnderstand your eligibility for tax credits and deductionsStay up-to-date on tax rules and breaksReady to Reduce Your Tax Liability? Contact Us NowGive us a call @ 1.877.776.6829 or visit our website Conciergetax.vip todayFinal note: Effective tax planning is an ongoing process. Start early, take small steps, and don’t hesitate to ask for help—a lower tax bill is within reach.

09.23.2026

Discover the Hidden Power of Legal Tax Mitigation Strategies Today

Imagine sitting at your kitchen table, sipping coffee on a sunny morning, and realizing your tax worries are melting away—not because you made money vanish, but because you understood and used the rules to your advantage. With the right legal tax mitigation strategies, everyday people and small business owners can transform tax season from a stress-inducing ordeal into a calculated step toward financial success. This guide uncovers how simple, compliant choices can help you keep more of what you earn. Unveiling Legal Tax Mitigation Strategies for Financial Peace of Mind The heart of effective tax planning isn’t about dodging the law—it’s about maximizing your opportunities within it. Legal tax mitigation strategies can make a significant difference by reducing your income tax liabilities, growing your wealth for retirement, and protecting your investments. Whether you’re managing a household budget or running a small business, understanding the tools available—such as IRAs, savings accounts, and credits—gives you power over your money. By familiarizing yourself with key topics like the differences between a Roth IRA and a Traditional IRA, understanding capital gains taxes, and tapping into the expertise of a tax advisor, you make each tax year a smoother process. Let’s dive into the transformative basics and practical steps anyone can take—without becoming an accountant. An everyday scenario: Navigating taxes with confidence Take Sarah and Mike, who once found April’s tax deadline overwhelming. By using a few essential legal tax mitigation strategies—like contributing to a traditional IRA and tracking allowable itemized deductions—they now approach tax time with planning, not panic. Their story is common: gaining knowledge, making a plan, and turning anxiety into empowerment. With some consistency and a little help, you can do the same. As you read on, you’ll discover not just how to save on taxes, but how to safely and confidently integrate these lessons into your everyday financial decisions. What You'll Learn About Legal Tax Mitigation Strategies The basics of legal tax mitigation strategies and their importance Essential tax planning concepts everyone should know Popular strategies for individuals and small businesses Key differences between Roth IRA and Traditional IRA for tax planning How capital gains and savings accounts factor into your approach When to consult a tax advisor Understanding Legal Tax Mitigation Strategies: Foundations and Importance Defining Legal Tax Mitigation Strategies Simply put, legal tax mitigation strategies are techniques used to minimize the amount of taxes owed through methods permitted by tax law. These include using available deductions, contributing to certain savings or investment accounts, carefully timing when you receive income or sell assets, and selecting the right retirement plan. Unlike illegal tactics that try to evade taxes, these practices are not only approved, but encouraged by the government to incentivize saving, investing, and charitable giving. For example, by maximizing permitted IRA and 401(k) contributions, tracking itemized deductions, and managing capital gains through strategic sales, taxpayers can align with both the spirit and the letter of the law. These strategies are tools—available to anyone willing to plan ahead. Why Everyone Needs to Know Legal Tax Mitigation Strategies You don’t need to be a millionaire or run a large company to benefit from tax planning. Anyone earning income—whether through a job, running a small business, or investing in real estate—can make small, legal adjustments that add up over time. By learning and applying these strategies early, you can lower your effective tax rate, keep more of your gross income, and gain more control over your financial future. Knowledge is key: the tax code may seem overwhelming, but a few well-understood basics can lead to years of savings. Whether you’re claiming the standard deduction or maximizing your health plan contributions, every bit counts—especially as laws change and new tax-saving opportunities emerge. When in doubt, a reputable tax advisor can guide you confidently through the process. Core Concepts in Tax Planning for Effective Legal Tax Mitigation Strategies Building Tax Planning Into Your Financial Routine Effective tax planning isn’t a once-a-year scramble. It’s about integrating smart habits into your day-to-day financial life—tracking expenses, understanding when to use itemized deductions over the standard deduction, and ensuring your adjusted gross income stays within optimal tax brackets. Consistency is crucial: reviewing your income tax choices with each big milestone (a new job, home purchase, or child’s birth) keeps you prepared. For instance, if you receive a year-end bonus, investing it in a retirement plan like a 401(k) or IRA may reduce your current year’s tax burden. Keeping records of charitable donations and medical expenses can also maximize eligible itemized deductions. Simple steps—done throughout the year—build a strong foundation for tax-efficient living. Leveraging Qualified Retirement Plans for Tax Benefits Qualified retirement plans offer two major tax advantages: upfront deductions and long-term tax-free growth. The traditional IRA lets you lower your adjusted gross income now by making pre-tax contributions, reducing your current-year taxable income. In contrast, the Roth IRA accepts after-tax dollars, but rewards you later with tax-free withdrawals in retirement. Choosing the right account depends on your current and expected tax bracket. Contributing to a Traditional IRA: Reduce current taxable income through pre-tax contributions. Opting for a Roth IRA: Pay taxes now for tax-free growth and withdrawals in retirement. Both options can be part of a broad tax planning strategy. Many savers opt to split contributions, hedging future tax law changes and offering themselves more flexibility in retirement. Exploring Account Types: Savings Accounts, IRAs, and More Using Savings Accounts for Tax-Efficient Growth While basic savings accounts don’t offer the same immediate deductions as IRAs, they remain valuable for building emergency funds and achieving short-term goals. Interest earned on these accounts is typically taxed as ordinary income, and while rates are modest, keeping a portion of your portfolio liquid and safe is crucial for weathering the unexpected. However, some health plans like HSAs (Health Savings Accounts) and 529 college savings plans amplify your tax savings beyond basic accounts—offering tax-deferred or tax-free growth for qualified expenses. Integrating a mix of account types creates balance: safety for today, and tax-efficient growth for tomorrow. Traditional IRA vs. Roth IRA: Which Is Best for Legal Tax Mitigation Strategies? Choosing between a traditional IRA and a Roth IRA is a core tax planning decision. Each has distinct benefits—and the right choice depends on whether you need tax relief today or are planning for a lower tax rate in retirement. We break down the essentials: Roth IRA Traditional IRA No deduction but tax-free withdrawals Contributions may be tax-deductible Taxes paid upfront; no taxes later Taxes paid on withdrawal No RMDs Required minimum distributions (RMDs) Ideal if you expect higher taxes in the future Beneficial for those anticipating lower income in retirement Evaluate your future needs, current tax bracket, and consult with a tax advisor for a tailored strategy. "The best time to start thinking about taxes is before the tax year begins. Early planning puts you in control." — Tax Advisor Insight Capital Gains: Minimizing Taxes on Investments with Legal Tax Mitigation Strategies Short-Term vs. Long-Term Capital Gains in Tax Planning Taxes on investment profits—known as capital gains—vary based on how long you hold your asset. Short-term capital gains, from assets held less than a year, are taxed as ordinary income at your regular rate. Long-term capital gains, from sales after more than a year, usually benefit from a lower capital gains tax rate. This difference can be significant, impacting your after-tax returns. Smart investors plan sales to maximize long-term gains, avoid unnecessary gains tax, and use strategies like loss harvesting to offset profits with losses. These distinctions matter even more in years when you sell large real estate holdings, stocks, or other major investments. Smart Strategies for Reducing Capital Gains Taxes Reducing your capital gains taxes isn’t about avoiding your obligations—it’s about using the flexibility tax law provides: Harvest investment losses to offset gains Utilize tax-exempt investment accounts Time asset sales for optimal tax years For example, selling lower-performing stocks to offset winnings can blunt the income tax impact in a volatile market year. Considerations like these are why proactive tax planning pays off not just for you, but for your entire family’s financial outlook. Federal Tax Law and Legal Tax Mitigation Strategies Understanding Federal Tax Provisions You Can Use Current federal tax laws offer plenty of tools for taxpayers seeking legal reductions. The standard deduction makes filing easy for most, but if your itemized deductions—like charitable deductions or state and local taxes—exceed it, you may save more by itemizing. Recognizing which credits you qualify for (education, energy-saving home upgrades, child tax credits) can also make a notable difference. Many changes to tax law and tax rates happen each year, so reviewing your options at least annually—and when your personal situation changes—is advisable. Always consider your adjusted gross income, filing status, and potential for new deductions or credits. Staying current can maximize your legal tax savings. The Role of a Tax Advisor in Legal Tax Mitigation Strategies A qualified tax advisor doesn’t just file forms—they guide your decisions and help you use every available legal strategy. These professionals understand evolving federal tax laws and can customize a tax planning approach for you or your business. With the right advisor, you’ll avoid costly errors, take full advantage of charitable deductions, and navigate complex topics like the IRS 7 year rule or retirement plan distributions. If your finances are complicated—perhaps involving multiple income sources, investment properties, or small business interests—a tax advisor is invaluable. They provide peace of mind and help you prepare for both current and future tax years. Legal Tax Mitigation Strategies for Small Business Owners Key Opportunities in Tax Planning for Businesses Small business owners can unlock a different set of legal tax mitigation strategies. Beyond maximizing retirement plan contributions, business owners can defer income to a future tax year, claim a broad range of business expenses, and use specialized accounts, like HSAs, for tax-advantaged savings. Proper tax planning also includes staying compliant with state and local taxes, managing inventory for optimal capital gains, and tracking qualified expenses for maximum deduction. Working with an experienced tax advisor ensures you don’t miss hidden opportunities, like the qualified business income deduction or retirement matching programs, creating powerful tools for business growth and personal savings alike. Popular Legal Tax Mitigation Strategies: A Quick List Maximize retirement plan contributions (Traditional IRA, Roth IRA, 401(k)) Defer income where possible Harvest capital losses Contribute to tax-advantaged accounts (HSAs, 529 plans) Claim all entitled credits and deductions Answers to Popular Legal Tax Mitigation Strategies Questions What are the best tax mitigation strategies? The most effective legal tax mitigation strategies involve consistent planning—contributing to IRAs and retirement accounts for deductions and future security, timing asset sales to maximize long-term capital gains tax preferences, and itemizing deductions when they exceed the standard deduction. Use tax-advantaged accounts like HSAs and 529s, and always stay informed about credits or changes to tax law that could work in your favor. Can I legally opt out of paying taxes? No, U. S. tax law requires all eligible individuals and businesses to pay federal tax on their income. However, you can use legal tax mitigation strategies to reduce your liability—such as contributing to retirement plans, utilizing credits, or claiming allowable itemized deductions—but total avoidance is illegal and can result in significant penalties. How can I legally reduce my income tax? Lowering your income tax legally comes down to maximizing deductions and credits (such as for dependents, education, or charitable donations), investing in retirement accounts like a Roth IRA or traditional IRA, and planning the timing of income or asset sales. Consulting a tax advisor ensures you navigate these opportunities correctly for your unique situation. What is the IRS 7 year rule? The IRS “7 year rule” generally refers to the recommended period for keeping back tax records and documentation, especially if you claim loss deductions for worthless securities or bad debt. While three years is often enough for standard returns, certain situations warrant holding onto records for up to seven years to be safe. Quick FAQs: Legal Tax Mitigation Strategies Is it legal to use deductions to lower taxes? Are Roth IRAs better for young savers? Do tax mitigation strategies work for business owners? How often should I review my tax plan? What role does a tax advisor play? Key Takeaways on Legal Tax Mitigation Strategies Legal tax mitigation strategies are essential tools for reducing tax liability and achieving peace of mind. Early and consistent tax planning leads to better outcomes. Retirement accounts such as Roth IRA and Traditional IRA are common vehicles. A knowledgeable tax advisor can help you navigate complexities and take advantage of legal opportunities. Expert tax advisor explains step-by-step legal tax mitigation strategies using diagrams and real-life examples in a 2-minute overview, shot in a modern office setting. Need Help With Legal Tax Mitigation Strategies? Give us a call @ 1. 877. 776. 6829 or visit our website Conciergetax. vip today for expert guidance tailored to your needs. Conclusion Incorporating legal tax mitigation strategies is your pathway to greater financial confidence, security, and long-term success. Start planning now, consult a trusted advisor, and turn your tax concerns into opportunities for growth. Sources https://www.fidelity.com/learning-center/personal-finance/how-to-reduce-taxable-income - 9 ways to potentially reduce your taxable incomehttps://www.ml.com/articles/tax-tips-that-could-save-you-money.html - 10 Tax Tips That Could Save You Money on Your Taxeshttps://www.fidelitycharitable.org/articles/six-tax-strategies-you-should-know.html - Six Tax Strategies You Should Knowhttps://www.edelmanfinancialengines.com/education/tax/14-tax-saving-strategies/ - 14 Tax Saving Strategies to Minimize Your Expenseshttps://www.fidelity.com/learning-center/personal-finance/tax-moves - Key tax moves for 2026https://privatebank.jpmorgan.com/nam/en/insights/markets-and-investing/ideas-and-insights/act-now-14-ways-to-lower-your-tax-bill - Act now: 14 ways to lower your tax billhttps://www.modernfamilyfinance.com/beyond-the-basics-tax-strategies-for-high-income-earners/ - Beyond the Basics: Tax strategies for High Income Earnershttps://www.morganstanley.com/articles/how-to-protect-your-income - 7 Steps That May Reduce Taxes on Your Income and ...

09.10.2026

What Most People Don’t Know About Cryptocurrency Taxes Demystified

Imagine the excitement of making your first crypto trade—only to discover there are tax rules and filing requirements you hadn’t planned for. Many new investors and even seasoned traders overlook key details that can complicate tax season and put you at risk of IRS scrutiny. This concise guide to cryptocurrency taxes demystified gives you the essential info and best practices to help you avoid costly mistakes and stay compliant.Shedding Light on Cryptocurrency Taxes DemystifiedImagine making your first crypto trade and suddenly hearing about taxes you didn’t expect—this guide explains why that happens and what you can do about it.Cryptocurrency taxes demystified is all about making the complex world of crypto tax obligations clear and approachable. Most people are caught off guard when they learn their digital asset activity—like trading, selling, or even spending crypto—often triggers tax consequences, even though “holding” crypto is not taxable. In this section, you’ll discover why crypto taxes matter, how the IRS views digital assets, and the importance of proper record keeping and tax reporting. Whether you’re a new investor or already trading different coins, understanding these rules is crucial to avoiding penalties, missed deductions, or audit headaches. Cryptocurrency is exciting, but when it comes to compliance, the IRS treats digital currency transactions much like those of stocks or other investments. With the growing scrutiny from regulators, being proactive is your best strategy.What You'll Learn About Cryptocurrency Taxes DemystifiedThe basics of crypto taxWhat counts as a taxable eventHow capital gains and losses workEssential tax forms and reporting tipsCommon crypto tax misconceptionsUnderstanding Crypto Taxes: How Cryptocurrency Taxes Demystified Helps You Stay CompliantGrasping cryptocurrency taxes demystified begins with knowing which actions are taxable and the different ways digital assets are reported to the IRS. Crypto tax rules classify most currency transactions—beyond just selling for cash—as potential taxable events. These requirements apply to gains and losses from trading coins, using crypto for goods or services, and even earning coins from work, mining, or staking. Staying compliant means understanding IRS requirements, tracking each transaction, and accurately reporting the capital gain or loss on your tax return. The IRS has increased its focus on tax compliance for digital assets and issues notices requiring clear and complete records of every purchase, sale, and trade. By staying up to date with these regulations, you can avoid the risk of penalties and leverage deductions for losses or expenses where applicable.What Is Considered a Taxable Event in Crypto Taxes?BuyingSellingTrading different coinsUsing crypto for purchasesEarning crypto as incomeA taxable event is any action that the IRS considers as creating a gain or loss for tax purposes, and this is essential to understanding cryptocurrency taxes demystified. For crypto assets, this includes selling crypto for cash, trading one type of coin for another, using tokens to pay for goods or services, and earning coins through income-generating activities like mining or staking. Importantly, simply buying or holding crypto does not count as taxable until you sell or otherwise dispose of it. Recognizing all forms of taxable currency transactions helps ensure you're tracking activity instead of missing key events that need to be included in your tax report.For those just starting out, missing a taxable event—like swapping Bitcoin for Ethereum—could mean inaccurate records come tax time. Using crypto tax software or working with a tax advisor can help you properly classify every potential taxable event. The key takeaway: knowing when your actions trigger a tax liability forms the foundation to stay on the right side of crypto tax law.Explaining Capital Gain and Capital Gains TaxDefinition of capital gain and capital gains taxDifference between short-term and long-term capital gainsReal-world examplesYour capital gain is the profit when you sell a crypto asset for more than you paid for it (your cost basis). When you dispose of digital assets—by selling or trading, for example—you must calculate your gain or loss based on the current fair market value compared to your initial purchase price. The capital gains tax applies to this profit. There are two main types: short-term capital gains (for assets held less than a year, taxed as ordinary income) and long-term capital gains (for assets held longer than a year, taxed at a potentially lower rate).For instance, if you bought Bitcoin at $4,000 and sold it at $6,500 after holding it for 16 months, the $2,500 profit is a long-term capital gain and may be taxed at a reduced tax rate. However, if you made that sale after only five months, it’s a short-term capital gain, usually taxed at the same rate as your salary or wages. Understanding these distinctions protects you from under- or over-reporting and helps maximize potential savings when properly reporting on your tax form.Understanding Gains and Losses for Crypto Taxes DemystifiedHow to track gains and losses on cryptocurrencyTax rules for reporting bothTracking gains and losses from crypto activity is one of the most important—and challenging—parts of compliant tax reporting. Every sale or trade of digital assets must be recorded with details: purchase price, sale price, date, and the specific asset involved. This enables you to determine the net gain or loss for each transaction, then total them for your annual return. Accurate records let you report capital gains and losses on IRS forms 8949 and Schedule D. Software tools and spreadsheet templates make it easier to track, categorize, and export this information for your tax return.By maintaining well-organized records, you can fully claim allowable capital losses which may offset gains elsewhere, reducing your total tax bill. But missing even a few transactions—or mixing up short-term and long-term holdings—can result in an incorrect tax report and potential IRS issues. The bottom line: don’t overlook losses, and always double-check your records before filing.Cost Basis Calculation for Cryptocurrency Taxes DemystifiedAt the heart of cryptocurrency taxes demystified is the concept of cost basis. Cost basis is the original value of an asset for tax purposes, typically what you paid plus any fees, and is critical when calculating capital gains and losses. The IRS lets you choose between different methods—like FIFO (First In, First Out), LIFO (Last In, First Out), or Specific Identification—for tracking which coins are being sold or traded. The method you choose affects the size of your gain or loss and, consequently, your tax obligation. If your records are incomplete or the chosen calculation method is inconsistent, the IRS may challenge your reported figures.What Is Cost Basis and Why Does It Matter for Crypto Tax?Definition of cost basisMethods for calculating cost basisImpact on capital gains and lossesCost basis determines your real profit or loss and is fundamental for cryptocurrency taxes demystified. Think of it as your purchase price—including any transaction fees you paid. When you sell, trade, or spend your coins, subtract your cost basis from the fair market value (FMV) at the time of sale to find your gain or loss. There are several acceptable ways to calculate cost basis: FIFO (first coins bought are the first sold), LIFO (the most recent coins bought are the first sold), and Specific Identification, which lets you assign particular coins with their purchase price to each sale.Choosing a cost basis method and applying it consistently to your records helps ensure you report the right amount of capital gain or loss and avoid IRS penalties. This process can be complex if you have lots of currency transactions or coins purchased at different times and prices. Crypto tax software or professional advice can make tracking and calculation easier, lowering your risk of audits or underreported gains.Tax Forms and Reporting: Navigating Cryptocurrency Taxes DemystifiedWhen tax season rolls around, being familiar with the correct tax forms for cryptocurrency transactions is key. The IRS has standardized forms used for reporting capital gains and losses, income from crypto, and special scenarios like airdrops. Proper tax reporting ensures your crypto activity is legally documented, reducing risk and giving you peace of mind. Leveraging these forms also lets you capture allowable capital loss deductions, maximizing your potential refund or lowering your overall tax bill. Knowing which forms apply based on your activity—selling, trading, earning—is fundamental for a smooth tax experience.Key Crypto Tax Forms You’ll Need8949Schedule D1040Other common formsForm 8949 is where you list all capital gains and losses from selling or trading crypto. These entries are then summarized on Schedule D, which is included as part of your annual 1040 federal tax return. If you earned income—such as from mining, staking, or payment for services—report it as ordinary income on form 1040 or a business schedule. Other tax forms may be required in special circumstances, like reporting foreign accounts holding crypto. Staying informed about these requirements ensures your tax return reflects your digital asset activity completely and correctly.Filing Tips for Cryptocurrency Taxes DemystifiedKeeping detailed recordsUsing crypto tax softwareWhen to seek professional guidanceAccurate filing is all about preparation and diligence. Start by keeping thorough records of every transaction including dates, amounts, counterparties, and the fair market value at the time of each trade. While some exchanges offer transaction histories, don’t rely only on platform reports—check for missing data, and supplement as needed. Crypto tax software can automate much of the data collection, cost basis calculation, and tax report generation, making life easier at tax time. If your portfolio is complex, involves multiple wallets or exchanges, or you’re unsure about IRS rules, seeking help from a crypto tax advisor or financial professional can save time, money, and headaches. A trusted expert will also keep you up to date with IRS notice changes, avoiding improper or late filings.Special Cases: Crypto Taxes Demystified for Hard Forks and AirdropsHow hard forks are taxedTax treatment of airdropped coinsSpecial events like hard forks and airdrops are unique to digital assets and bring their own tax implications. A hard fork happens when a blockchain splits and you receive new coins as a result. According to IRS guidance, this is generally treated as ordinary income equal to the fair market value of the new coins received at the time they’re accessible.Similarly, if you receive airdropped coins, their fair market value at receipt is recognized as taxable income and reported on your tax return. Both cases trigger tax events regardless of whether you sell or hold the new coins—so keeping close records is crucial. If you later sell or exchange those coins, that becomes a separate taxable event, with cost basis set at the FMV upon receipt.Income Tax and Cryptocurrency Taxes DemystifiedNot all crypto taxes involve capital gains—some crypto income is treated as regular ordinary income instead. If you earn crypto through mining, staking, or as payment for services, these amounts are taxed as income at their fair market value when received. Then, if you later sell or trade those coins, the usual capital gain or loss rules apply based on their value when you acquired them. This dual taxation structure—income tax at collection, capital gains at disposal—makes clear records and separation of events vital.When Is Crypto Treated as Income for Tax Purposes?MiningStakingPayment for servicesAny time you acquire digital assets through mining, staking, or as direct payment for goods or services, the IRS considers the fair market value at receipt to be taxable income. This differs from simply buying or holding coins, which isn’t taxed until you sell. These amounts are reported as part of your 1040 income tax return, and are taxed at ordinary income tax rates. Keeping track of the value when you receive coins is essential for both your income tax and setting the correct cost basis if you later sell those assets.For example, miners who receive crypto as a block reward must report the current market price as income even if they don’t immediately convert it to cash. Professionals who accept digital asset payments for services must also report the dollar value received as income. This distinction between earning and investing is fundamental for compliance.Tax Rate Considerations for Crypto Taxes DemystifiedHow tax rates apply to crypto income and gainsIntroduction to relevant bracketsThe tax rate that applies to your crypto depends on the type of transaction. Income from mining, staking, or business services is taxed at your ordinary income tax rate, which rises with your overall income and can hit higher federal tax brackets. In contrast, capital gains are split into short-term (taxed as ordinary income if held less than a year) and long-term (typically taxed at 0%, 15%, or 20% depending on your total income). Knowing which bracket you fall into and planning sales accordingly can help minimize your overall crypto tax liability.It’s also important to stay current with IRS guidelines, as rates and brackets are periodically reviewed and updated. Specialized circumstances—such as large one-time sales or a combination of crypto income types—may call for working with a tax advisor to ensure you’re taking advantage of all available deductions and credits.Common Misconceptions About Cryptocurrency Taxes DemystifiedCrypto is anonymous and untaxedSmall transactions don’t need reportingOnly cashing out triggers taxesMany mistakenly believe that crypto is either anonymous or goes under the IRS radar, but recent IRS notice campaigns and platform reporting requirements prove otherwise. No matter the size, any taxable transaction—even a cup of coffee bought with Bitcoin—should be included in your tax report. Another common myth is that only “cashing out” to fiat triggers tax; in reality, trades, exchanges, and even earning coins through rewards or work all count as taxable events. Misinformation or misunderstanding these nuances leads to underreporting, penalties, and missed tax planning opportunities.Strategies to Stay Ahead on Cryptocurrency Taxes DemystifiedOrganizing records throughout the yearConsidering tax-loss harvestingStaying updated on tax law changesProactive planning is the best way to simplify cryptocurrency taxes demystified. Start by logging every transaction as it happens, including deposits, withdrawals, trades, and airdrops. Don’t rely on exchanges to keep perfect records—backup your own and audit periodically. Consider tax-loss harvesting: if you have coins that have declined in value, you may be able to use those losses to offset gains elsewhere for the same year. And with tax law for digital assets evolving fast, subscribe to updates from the IRS or rely on a professional to keep your approach current. Consistency and diligence now can save time, stress, and money at tax season.Table: Comparison of Tax Treatment for Different Crypto ActivitiesActivityTaxableExample Tax FormBuyingNo-SellingYes8949, Schedule DTradingYes8949, Schedule DEarning IncomeYes1040Hard Fork/AirdropYes1040Quotes from Tax Experts on Cryptocurrency Taxes Demystified"Understanding your cost basis and accurately tracking your trades are crucial steps to avoid headaches and penalties from the IRS." – Crypto Tax AdvisorLists: Best Practices for Filing Cryptocurrency Taxes DemystifiedLog every transactionDon’t rely solely on exchanges for recordsDouble-check all tax forms before submittingSet aside funds for taxes owedPeople Also Ask About Cryptocurrency Taxes DemystifiedAt what point do I have to pay taxes on crypto?You typically owe taxes when you realize a gain—such as selling, exchanging, or using crypto for purchases. Simply holding isn’t taxable.Will you be taxed for a $1000 in crypto profit?Yes, a $1,000 profit from selling or exchanging crypto is considered a taxable gain and must be reported on your tax return.How much capital gains tax will I pay on $300,000?The rate depends on your holding period and tax bracket. Long-term capital gains (over one year) are taxed at a lower rate compared to short-term gains (under a year), which are taxed as ordinary income.How will crypto be taxed in 2026?Although tax laws can change, most experts predict continued scrutiny, with more detailed reporting requirements and possible adjustments to rates or brackets.FAQs: Quick Answers about Cryptocurrency Taxes DemystifiedDo I need to pay tax if I never sold my crypto? (No, only realized gains are taxable.)Are crypto gifts taxable? (Usually not for the recipient, but the giver may need to file.)Can I deduct trading losses? (Yes, up to certain IRS limits.)Key Takeaways from Cryptocurrency Taxes DemystifiedAlmost every cryptocurrency transaction can be a taxable eventAccurate record keeping is keySeek informed guidance to avoid mistakesReady for Tax Season? Expert Assistance for Cryptocurrency Taxes DemystifiedHave questions about navigating crypto taxes? Give us a call @ 1.877.776.6829 or visit our website Conciergetax.vip today for tailored advice.ConclusionStay proactive: log every transaction, double-check your records, and consult an expert when needed to make cryptocurrency taxes demystified a breeze.Sourceshttps://www.fidelity.com/learning-center/trading-investing/crypto/crypto-taxes-explained - Crypto taxes explained | Fidelityhttps://www.morganstanley.com/insights/articles/crypto-taxes-investor-guide - Crypto Taxes, Explained: Wallets, Stocks, Funds and Futureshttps://ltaxconsulting.com/blog/crypto-tax-2025-demystified-everything-you-need-to-know-to-stay-compliant - Crypto Tax 2025 Demystified: Everything You Need to ...https://turbotax.intuit.com/tax-tips/investments-and-taxes/your-cryptocurrency-tax-guide/L4k3xiFjB - Your Crypto Tax Guide - TurboTax - Intuithttps://coinledger.io/guides/crypto-tax - Crypto Taxes: The Complete Guide (2026)https://bipartisanpolicy.org/issue-brief/how-is-cryptocurrency-taxed-current-rules-and-outstanding-questions/ - How Is Cryptocurrency Taxed? Current Rules and ...

Contact:

T: +1 833 229 5500

Email: connect@keithstoller.com

About Us:

Keith Stoller coaches businesses for quick breakthroughs that foster long-lasting success.

© 2026 Stoller Companies LLC All Rights Reserved. 9350 Wilshire Blvd, Suite 203-E81 , Beverly Hills , CA 90212. Contact Us. Terms of Service . Privacy Policy

ewogICJjb21wYW55IjogIltDb21wYW55IE5hbWVdIiwKICAiYWRkcmVzcyI6ICJbQ29tcGFueSBBZGRyZXNzXSIsCiAgImNpdHkiOiAiW0NvbXBhbnkgQ2l0eV0iLAogICJzdGF0ZSI6ICJbQ29tcGFueSBTdGF0ZV0iLAogICJ6aXAiOiAiW1Bvc3RhbCBDb2RlXSIsCiAgImVtYWlsIjogIltDb21wYW55IEVtYWlsXSIsCiAgInRvcyI6ICJDanh3UGp4emRISnZibWMrUEdWdFBsZG9aVzRnZVc5MUlITnBaMjR0YVc0Z2QybDBhQ0IxY3l3Z2VXOTFJR0Z5WlNCbmFYWnBibWNtYm1KemNEc2dlVzkxY2lCd1pYSnRhWE56YVc5dUlHRnVaQ0JqYjI1elpXNTBJSFJ2SUhObGJtUWdlVzkxSUdWdFlXbHNJR0Z1WkM5dmNpQlRUVk1nZEdWNGRDQnRaWE56WVdkbGN5NGdRbmtnWTJobFkydHBibWNnZEdobElGUmxjbTF6SUdGdVpDQkRiMjVrYVhScGIyNXpJR0p2ZUNCaGJtUWdZbmtnYzJsbmJtbHVaeUJwYmlCNWIzVWdZWFYwYjIxaGRHbGpZV3hzZVNCamIyNW1hWEp0SUhSb1lYUWdlVzkxSUdGalkyVndkQ0JoYkd3Z2RHVnliWE1nYVc0Z2RHaHBjeUJoWjNKbFpXMWxiblF1UEM5bGJUNDhMM04wY205dVp6NDhMM0ErQ2p4d1BpWnVZbk53T3p3dmNENEtQSEErUEhOMGNtOXVaejVUUlZKV1NVTkZQQzl6ZEhKdmJtYytQQzl3UGdvOGNENVhaU0J3Y205MmFXUmxJR0VnYzJWeWRtbGpaU0IwYUdGMElHTjFjbkpsYm5Sc2VTQmhiR3h2ZDNNZ2VXOTFJSFJ2SUhKbFkyVnBkbVVnY21WeGRXVnpkSE1nWm05eUlHWmxaV1JpWVdOckxDQmpiMjF3WVc1NUlHbHVabTl5YldGMGFXOXVMQ0J3Y205dGIzUnBiMjVoYkNCcGJtWnZjbTFoZEdsdmJpd2dZMjl0Y0dGdWVTQmhiR1Z5ZEhNc0lHTnZkWEJ2Ym5Nc0lHUnBjMk52ZFc1MGN5QmhibVFnYjNSb1pYSWdibTkwYVdacFkyRjBhVzl1Y3lCMGJ5QjViM1Z5SUdWdFlXbHNJR0ZrWkhKbGMzTWdZVzVrTDI5eUlHTmxiR3gxYkdGeUlIQm9iMjVsSUc5eUlHUmxkbWxqWlM0Z1dXOTFJSFZ1WkdWeWMzUmhibVFnWVc1a0lHRm5jbVZsSUhSb1lYUWdkR2hsSUZObGNuWnBZMlVnYVhNZ2NISnZkbWxrWldRZ0puRjFiM1E3UVZNdFNWTW1jWFZ2ZERzZ1lXNWtJSFJvWVhRZ2QyVWdZWE56ZFcxbElHNXZJSEpsYzNCdmJuTnBZbWxzYVhSNUlHWnZjaUIwYUdVZ2RHbHRaV3hwYm1WemN5d2daR1ZzWlhScGIyNHNJRzFwY3kxa1pXeHBkbVZ5ZVNCdmNpQm1ZV2xzZFhKbElIUnZJSE4wYjNKbElHRnVlU0IxYzJWeUlHTnZiVzExYm1sallYUnBiMjV6SUc5eUlIQmxjbk52Ym1Gc2FYcGhkR2x2YmlCelpYUjBhVzVuY3k0OEwzQStDanh3UGxsdmRTQmhjbVVnY21WemNHOXVjMmxpYkdVZ1ptOXlJRzlpZEdGcGJtbHVaeUJoWTJObGMzTWdkRzhnZEdobElGTmxjblpwWTJVZ1lXNWtJSFJvWVhRZ1lXTmpaWE56SUcxaGVTQnBiblp2YkhabElIUm9hWEprSUhCaGNuUjVJR1psWlhNZ0tITjFZMmdnWVhNZ1UwMVRJSFJsZUhRZ2JXVnpjMkZuWlhNc0lFbHVkR1Z5Ym1WMElITmxjblpwWTJVZ2NISnZkbWxrWlhJZ2IzSWdZMlZzYkhWc1lYSWdZV2x5ZEdsdFpTQmphR0Z5WjJWektTNGdXVzkxSUdGeVpTQnlaWE53YjI1emFXSnNaU0JtYjNJZ2RHaHZjMlVnWm1WbGN5d2dhVzVqYkhWa2FXNW5JSFJvYjNObElHWmxaWE1nWVhOemIyTnBZWFJsWkNCM2FYUm9JSFJvWlNCa2FYTndiR0Y1SUc5eUlHUmxiR2wyWlhKNUlHOW1JR1ZoWTJnZ1UwMVRJSFJsZUhRZ2JXVnpjMkZuWlNCelpXNTBJSFJ2SUhsdmRTQmllU0IxY3k0Z1NXNGdZV1JrYVhScGIyNHNJSGx2ZFNCdGRYTjBJSEJ5YjNacFpHVWdZVzVrSUdGeVpTQnlaWE53YjI1emFXSnNaU0JtYjNJZ1lXeHNJR1Z4ZFdsd2JXVnVkQ0J1WldObGMzTmhjbmtnZEc4Z1lXTmpaWE56SUhSb1pTQlRaWEoyYVdObElHRnVaQ0J5WldObGFYWmxJSFJvWlNCVFRWTWdkR1Y0ZENCdFpYTnpZV2RsY3k0Z1YyVWdaRzhnYm05MElHTm9ZWEpuWlNCaGJua2dabVZsY3lCbWIzSWdaR1ZzYVhabGNua2diMllnWlcxaGFXd2diM0lnVTAxVExpQlVhR2x6SUdseklHRWdabkpsWlNCelpYSjJhV05sSUhCeWIzWnBaR1ZrSUdKNUlIVnpMaUJJYjNkbGRtVnlMQ0J3YkdWaGMyVWdZMmhsWTJzZ2QybDBhQ0I1YjNWeUlHbHVkR1Z5Ym1WMElITmxjblpwWTJVZ2NISnZkbWxrWlhJZ1lXNWtJR05sYkd4MWJHRnlJR05oY25KcFpYSWdabTl5SUdGdWVTQmphR0Z5WjJWeklIUm9ZWFFnYldGNUlHbHVZM1Z5SUdGeklHRWdjbVZ6ZFd4MElHWnliMjBnY21WalpXbDJhVzVuSUdWdFlXbHNJR0Z1WkNCVFRWTWdkR1Y0ZENCdFpYTnpZV2RsY3lCMGFHRjBJSGRsSUdSbGJHbDJaWElnZFhCdmJpQjViM1Z5SUc5d2RDMXBiaUJoYm1RZ2NtVm5hWE4wY21GMGFXOXVJSGRwZEdnZ2IzVnlJR1Z0WVdsc0lHRnVaQ0JUVFZNZ2MyVnlkbWxqWlhNdUlGbHZkU0JqWVc0Z1kyRnVZMlZzSUdGMElHRnVlU0IwYVcxbExpQktkWE4wSUhSbGVIUWdKbkYxYjNRN1UxUlBVQ1p4ZFc5ME95QjBieVp1WW5Od096eG9hV2RvYkdsbmFIUWdZMnhoYzNNOUltTnZiWEJoYm5sVFRWTlFhRzl1WlZWd1pHRjBaU0krUEM5b2FXZG9iR2xuYUhRK0xpQkJablJsY2lCNWIzVWdjMlZ1WkNCMGFHVWdVMDFUSUcxbGMzTmhaMlVnSm5GMWIzUTdVMVJQVUNaeGRXOTBPeUIwYnlCMWN5d2dkMlVnZDJsc2JDQnpaVzVrSUhsdmRTQmhiaUJUVFZNZ2JXVnpjMkZuWlNCMGJ5QmpiMjVtYVhKdElIUm9ZWFFnZVc5MUlHaGhkbVVnWW1WbGJpQjFibk4xWW5OamNtbGlaV1F1SUVGbWRHVnlJSFJvYVhNc0lIbHZkU0IzYVd4c0lHNXZJR3h2Ym1kbGNpQnlaV05sYVhabElGTk5VeUJ0WlhOellXZGxjeUJtY205dElIVnpMand2Y0Q0S1BIQStQSE4wY205dVp6NVpUMVZTSUZKRlIwbFRWRkpCVkVsUFRpQlBRa3hKUjBGVVNVOU9Vend2YzNSeWIyNW5Qand2Y0Q0S1BIQStTVzRnWTI5dWMybGtaWEpoZEdsdmJpQnZaaUI1YjNWeUlIVnpaU0J2WmlCMGFHVWdVMlZ5ZG1salpTd2dlVzkxSUdGbmNtVmxJSFJ2T2p3dmNENEtQRzlzUGdvZ0lDQWdQR3hwUG5CeWIzWnBaR1VnZEhKMVpTd2dZV05qZFhKaGRHVXNJR04xY25KbGJuUWdZVzVrSUdOdmJYQnNaWFJsSUdsdVptOXliV0YwYVc5dUlHRmliM1YwSUhsdmRYSnpaV3htSUdGeklIQnliMjF3ZEdWa0lHSjVJSFJvWlNCVFpYSjJhV05sSmlNek9UdHpJSEpsWjJsemRISmhkR2x2YmlCbWIzSnRJQ2h6ZFdOb0lHbHVabTl5YldGMGFXOXVJR0psYVc1bklIUm9aU0FtY1hWdmREdFNaV2RwYzNSeVlYUnBiMjRnUkdGMFlTWnhkVzkwT3lrZ1lXNWtQQzlzYVQ0S0lDQWdJRHhzYVQ1dFlXbHVkR0ZwYmlCaGJtUWdjSEp2YlhCMGJIa2dkWEJrWVhSbElIUm9aU0JTWldkcGMzUnlZWFJwYjI0Z1JHRjBZU0IwYnlCclpXVndJR2wwSUhSeWRXVXNJR0ZqWTNWeVlYUmxMQ0JqZFhKeVpXNTBJR0Z1WkNCamIyMXdiR1YwWlM0Z1NXWWdlVzkxSUhCeWIzWnBaR1VnWVc1NUlHbHVabTl5YldGMGFXOXVJSFJvWVhRZ2FYTWdkVzUwY25WbExDQnBibUZqWTNWeVlYUmxMQ0J1YjNRZ1kzVnljbVZ1ZENCdmNpQnBibU52YlhCc1pYUmxMQ0J2Y2lCM1pTQm9ZWFpsSUhKbFlYTnZibUZpYkdVZ1ozSnZkVzVrY3lCMGJ5QnpkWE53WldOMElIUm9ZWFFnYzNWamFDQnBibVp2Y20xaGRHbHZiaUJwY3lCMWJuUnlkV1VzSUdsdVlXTmpkWEpoZEdVc0lHNXZkQ0JqZFhKeVpXNTBJRzl5SUdsdVkyOXRjR3hsZEdVc0lIZGxJR2hoZG1VZ2RHaGxJSEpwWjJoMElIUnZJSE4xYzNCbGJtUWdiM0lnUEhOMGNtOXVaejQ4YzNCaGJpQnpkSGxzWlQwaVkyOXNiM0k2STBaR01EQXdNRHNpUG5SbGNtMXBibUYwWlNCNWIzVnlJR0ZqWTI5MWJuUXZjSEp2Wm1sc1pTQmhibVFnY21WbWRYTmxJR0Z1ZVNCaGJtUWdZV3hzSUdOMWNuSmxiblFnYjNJZ1puVjBkWEpsSUhWelpTQnZaaUIwYUdVZ1UyVnlkbWxqWlNBb2IzSWdZVzU1SUhCdmNuUnBiMjRnZEdobGNtVnZaaWt1UEM5emNHRnVQand2YzNSeWIyNW5Qand2YkdrK0Nqd3ZiMncrQ2p4d1BpWnVZbk53T3p3dmNENEtQR2hwWjJoc2FXZG9kQ0JqYkdGemN6MGlZMjl0Y0dGdWVVNWhiV1ZWY0dSaGRHVWlQbHREYjIxd1lXNTVJRTVoYldWZFBDOW9hV2RvYkdsbmFIUStQR0p5SUM4K0NqeG9hV2RvYkdsbmFIUWdZMnhoYzNNOUltTnZiWEJoYm5sQlpHUnlaWE56VlhCa1lYUmxJajViUTI5dGNHRnVlU0JCWkdSeVpYTnpYVHd2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ284YUdsbmFHeHBaMmgwSUdOc1lYTnpQU0pqYjIxd1lXNTVVR2h2Ym1WVmNHUmhkR1VpUGx0RGIyMXdZVzU1SUZCb2IyNWxYVHd2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ284YUdsbmFHeHBaMmgwSUdOc1lYTnpQU0pqYjIxd1lXNTVSVzFoYVd4VmNHUmhkR1VpUGx0RGIyMXdZVzU1SUVWdFlXbHNYVHd2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ289IiwKICAicHJpdmFjeSI6ICJDanh3UGp4emRISnZibWMrVUZKSlZrRkRXVHd2YzNSeWIyNW5Qand2Y0Q0S1BIQStQSE4wY205dVp6NVVhR1VnYVc1bWIzSnRZWFJwYjI0Z2NISnZkbWxrWldRZ1pIVnlhVzVuSUhSb2FYTWdjbVZuYVhOMGNtRjBhVzl1SUdseklHdGxjSFFnY0hKcGRtRjBaU0JoYm1RZ1kyOXVabWxrWlc1MGFXRnNMQ0JoYm1RZ2QybHNiQ0J1WlhabGNpQmlaU0JrYVhOMGNtbGlkWFJsWkN3Z1kyOXdhV1ZrTENCemIyeGtMQ0IwY21Ga1pXUWdiM0lnY0c5emRHVmtJR2x1SUdGdWVTQjNZWGtzSUhOb1lYQmxJRzl5SUdadmNtMHVJRlJvYVhNZ2FYTWdiM1Z5SUdkMVlYSmhiblJsWlM0OEwzTjBjbTl1Wno0OEwzQStDanh3UGp4emRISnZibWMrU1U1RVJVMU9TVlJaUEM5emRISnZibWMrUEM5d1BnbzhjRDQ4WlcwK1dXOTFJR0ZuY21WbElIUnZJR2x1WkdWdGJtbG1lU0JoYm1RZ2FHOXNaQ0IxY3l3dUlHRnVaQ0JwZEhNZ2MzVmljMmxrYVdGeWFXVnpMQ0JoWm1acGJHbGhkR1Z6TENCdlptWnBZMlZ5Y3l3Z1lXZGxiblJ6TENCamJ5MWljbUZ1WkdWeWN5QnZjaUJ2ZEdobGNpQndZWEowYm1WeWN5d2dZVzVrSUdWdGNHeHZlV1ZsY3l3Z2FHRnliV3hsYzNNZ1puSnZiU0JoYm5rZ1kyeGhhVzBnYjNJZ1pHVnRZVzVrTENCcGJtTnNkV1JwYm1jZ2NtVmhjMjl1WVdKc1pTQmhkSFJ2Y201bGVYTW1Jek01T3lCbVpXVnpMQ0J0WVdSbElHSjVJR0Z1ZVNCMGFHbHlaQ0J3WVhKMGVTQmtkV1VnZEc4Z2IzSWdZWEpwYzJsdVp5QnZkWFFnYjJZZ1EyOXVkR1Z1ZENCNWIzVWdjbVZqWldsMlpTd2djM1ZpYldsMExDQnlaWEJzZVN3Z2NHOXpkQ3dnZEhKaGJuTnRhWFFnYjNJZ2JXRnJaU0JoZG1GcGJHRmliR1VnZEdoeWIzVm5hQ0IwYUdVZ1UyVnlkbWxqWlN3Z2VXOTFjaUIxYzJVZ2IyWWdkR2hsSUZObGNuWnBZMlVzSUhsdmRYSWdZMjl1Ym1WamRHbHZiaUIwYnlCMGFHVWdVMlZ5ZG1salpTd2dlVzkxY2lCMmFXOXNZWFJwYjI0Z2IyWWdkR2hsSUZSUFV5d2diM0lnZVc5MWNpQjJhVzlzWVhScGIyNGdiMllnWVc1NUlISnBaMmgwY3lCdlppQmhibTkwYUdWeUxqd3ZaVzArUEM5d1BnbzhjRDQ4YzNSeWIyNW5Qa1JKVTBOTVFVbE5SVklnVDBZZ1YwRlNVa0ZPVkVsRlV6d3ZjM1J5YjI1blBqd3ZjRDRLUEhBK1BITjBjbTl1Wno1WlQxVWdSVmhRVWtWVFUweFpJRlZPUkVWU1UxUkJUa1FnUVU1RUlFRkhVa1ZGSUZSSVFWUTZQQzl6ZEhKdmJtYytQQzl3UGdvOGIydytDZ2s4YkdrK1dVOVZVaUJWVTBVZ1QwWWdWRWhGSUZORlVsWkpRMFVnU1ZNZ1FWUWdXVTlWVWlCVFQweEZJRkpKVTBzdUlGUklSU0JUUlZKV1NVTkZJRWxUSUZCU1QxWkpSRVZFSUU5T0lFRk9JQ1p4ZFc5ME8wRlRJRWxUSm5GMWIzUTdJRUZPUkNBbWNYVnZkRHRCVXlCQlZrRkpURUZDVEVVbWNYVnZkRHNnUWtGVFNWTXVJQ3d1SUVGT1JDQlZVeXdnU1ZRbUl6TTVPMU1nUTFWVFZFOU5SVkpUTENCRldGQlNSVk5UVEZrZ1JFbFRRMHhCU1UxVElFRk1UQ0JYUVZKU1FVNVVTVVZUSUU5R0lFRk9XU0JMU1U1RUxDQlhTRVZVU0VWU0lFVllVRkpGVTFNZ1QxSWdTVTFRVEVsRlJDd2dTVTVEVEZWRVNVNUhMQ0JDVlZRZ1RrOVVJRXhKVFVsVVJVUWdWRThnVkVoRklFbE5VRXhKUlVRZ1YwRlNVa0ZPVkVsRlV5QlBSaUJOUlZKRFNFRk9WRUZDU1V4SlZGa3NJRVpKVkU1RlUxTWdSazlTSUVFZ1VFRlNWRWxEVlV4QlVpQlFWVkpRVDFORklFRk9SQ0JPVDA0dFNVNUdVa2xPUjBWTlJVNVVMand2YkdrK0NnazhiR2srVFVGTFJWTWdUazhnVjBGU1VrRk9WRmtnVkVoQlZDQW9hU2tnVkVoRklGTkZVbFpKUTBVZ1YwbE1UQ0JOUlVWVUlGbFBWVklnVWtWUlZVbFNSVTFGVGxSVExDQW9hV2twSUZSSVJTQlRSVkpXU1VORklGZEpURXdnUWtVZ1ZVNUpUbFJGVWxKVlVGUkZSQ3dnVkVsTlJVeFpMQ0JUUlVOVlVrVXNJRTlTSUVWU1VrOVNMVVpTUlVVc0lDaHBhV2twSUZSSVJTQlNSVk5WVEZSVElGUklRVlFnVFVGWklFSkZJRTlDVkVGSlRrVkVJRVpTVDAwZ1ZFaEZJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JYU1V4TUlFSkZJRUZEUTFWU1FWUkZJRTlTSUZKRlRFbEJRa3hGTENCQlRrUWdLR2wyS1NCQlRsa2dSVkpTVDFKVElFbE9JRlJJUlNCVFQwWlVWMEZTUlNCWFNVeE1JRUpGSUVOUFVsSkZRMVJGUkM0OEwyeHBQZ29KUEd4cFBrRk9XU0JOUVZSRlVrbEJUQ0JFVDFkT1RFOUJSRVZFSUU5U0lFOVVTRVZTVjBsVFJTQlBRbFJCU1U1RlJDQlVTRkpQVlVkSUlGUklSU0JWVTBVZ1QwWWdWRWhGSUZORlVsWkpRMFVnU1ZNZ1JFOU9SU0JCVkNCWlQxVlNJRTlYVGlCRVNWTkRVa1ZVU1U5T0lFRk9SQ0JTU1ZOTElFRk9SQ0JVU0VGVUlGbFBWU0JYU1V4TUlFSkZJRk5QVEVWTVdTQlNSVk5RVDA1VFNVSk1SU0JHVDFJZ1FVNVpJRVJCVFVGSFJTQlVUeUJaVDFWU0lFTlBUVkJWVkVWU0lGTlpVMVJGVFNCUFVpQk1UMU5USUU5R0lFUkJWRUVnVkVoQlZDQlNSVk5WVEZSVElFWlNUMDBnVkVoRklFUlBWMDVNVDBGRUlFOUdJRUZPV1NCVFZVTklJRTFCVkVWU1NVRk1Mand2YkdrK0NnazhiR2srVGs4Z1FVUldTVU5GSUU5U0lFbE9SazlTVFVGVVNVOU9MQ0JYU0VWVVNFVlNJRTlTUVV3Z1QxSWdWMUpKVkZSRlRpd2dUMEpVUVVsT1JVUWdRbGtnV1U5VklFWlNUMDBnVDFJZ1ZFaFNUMVZIU0NCUFVpQkdVazlOSUZSSVJTQlRSVkpXU1VORklGTklRVXhNSUVOU1JVRlVSU0JCVGxrZ1YwRlNVa0ZPVkZrZ1RrOVVJRVZZVUZKRlUxTk1XU0JUVkVGVVJVUWdTVTRnVkVoRklGUlBVeTQ4TDJ4cFBnbzhMMjlzUGdvOGNENDhjM1J5YjI1blBreEpUVWxVUVZSSlQwNGdUMFlnVEVsQlFrbE1TVlJaUEM5emRISnZibWMrUEM5d1BnbzhjRDVaVDFVZ1JWaFFVa1ZUVTB4WklGVk9SRVZTVTFSQlRrUWdRVTVFSUVGSFVrVkZJRlJJUVZRZ1FVNUVJRk5JUVV4TUlFNVBWQ0JDUlNCTVNVRkNURVVnUms5U0lFRk9XU0JFU1ZKRlExUXNJRWxPUkVsU1JVTlVMQ0JKVGtOSlJFVk9WRUZNTENCVFVFVkRTVUZNTENCRFQwNVRSVkZWUlU1VVNVRk1JRTlTSUVWWVJVMVFURUZTV1NCRVFVMUJSMFZUTENCSlRrTk1WVVJKVGtjZ1FsVlVJRTVQVkNCTVNVMUpWRVZFSUZSUExDQkVRVTFCUjBWVElFWlBVaUJNVDFOVElFOUdJRkJTVDBaSlZGTXNJRWRQVDBSWFNVeE1MQ0JWVTBVc0lFUkJWRUVnVDFJZ1QxUklSVklnU1U1VVFVNUhTVUpNUlNCTVQxTlRSVk1nS0VWV1JVNGdTVVlnU0VGVElFSkZSVTRnUVVSV1NWTkZSQ0JQUmlCVVNFVWdVRTlUVTBsQ1NVeEpWRmtnVDBZZ1UxVkRTQ0JFUVUxQlIwVlRLU3dnVWtWVFZVeFVTVTVISUVaU1QwMDZQQzl3UGdvOGIydytDZ2s4YkdrK1ZFaEZJRlZUUlNCUFVpQlVTRVVnU1U1QlFrbE1TVlJaSUZSUElGVlRSU0JVU0VVZ1UwVlNWa2xEUlRzOEwyeHBQZ29KUEd4cFBsUklSU0JEVDFOVUlFOUdJRkJTVDBOVlVrVk5SVTVVSUU5R0lGTlZRbE5VU1ZSVlZFVWdSMDlQUkZNZ1FVNUVJRk5GVWxaSlEwVlRJRkpGVTFWTVZFbE9SeUJHVWs5TklFRk9XU0JIVDA5RVV5d2dSRUZVUVN3Z1NVNUdUMUpOUVZSSlQwNGdUMUlnVTBWU1ZrbERSVk1nVUZWU1EwaEJVMFZFSUU5U0lFOUNWRUZKVGtWRUlFOVNJRTFGVTFOQlIwVlRJRkpGUTBWSlZrVkVJRTlTSUZSU1FVNVRRVU5VU1U5T1V5QkZUbFJGVWtWRUlFbE9WRThnVkVoU1QxVkhTQ0JQVWlCR1VrOU5JRlJJUlNCVFJWSldTVU5GT3p3dmJHaytDZ2s4YkdrK1ZVNUJWVlJJVDFKSldrVkVJRUZEUTBWVFV5QlVUeUJQVWlCQlRGUkZVa0ZVU1U5T0lFOUdJRmxQVlZJZ1ZGSkJUbE5OU1ZOVFNVOU9VeUJQVWlCRVFWUkJPend2YkdrK0NnazhiR2srVTFSQlZFVk5SVTVVVXlCUFVpQkRUMDVFVlVOVUlFOUdJRUZPV1NCVVNFbFNSQ0JRUVZKVVdTQlBUaUJVU0VVZ1UwVlNWa2xEUlRzZ1QxSThMMnhwUGdvSlBHeHBQa0ZPV1NCUFZFaEZVaUJOUVZSVVJWSWdVa1ZNUVZSSlRrY2dWRThnVkVoRklGTkZVbFpKUTBVdVBDOXNhVDRLUEM5dmJENEtQSEErUEhVK1Fua2djbVZuYVhOMFpYSnBibWNnWVc1a0lITjFZbk5qY21saWFXNW5JSFJ2SUc5MWNpQmxiV0ZwYkNCaGJtUWdVMDFUSUhObGNuWnBZMlVzSUdKNUlHOXdkQzFwYml3Z2IyNXNhVzVsSUhKbFoybHpkSEpoZEdsdmJpQnZjaUJpZVNCbWFXeHNhVzVuSUc5MWRDQmhJR05oY21Rc0lDWnhkVzkwTzNsdmRTQmhaM0psWlNCMGJ5QjBhR1Z6WlNCVVJWSk5VeUJQUmlCVFJWSldTVU5GSm5GMWIzUTdJR0Z1WkNCNWIzVWdZV05yYm05M2JHVmtaMlVnWVc1a0lIVnVaR1Z5YzNSaGJtUWdkR2hsSUdGaWIzWmxJSFJsY20xeklHOW1JSE5sY25acFkyVWdiM1YwYkdsdVpXUWdZVzVrSUdSbGRHRnBiR1ZrSUdadmNpQjViM1VnZEc5a1lYa3VQQzkxUGp3dmNENEtQSEErSm01aWMzQTdQQzl3UGdvOGFHbG5hR3hwWjJoMElHTnNZWE56UFNKamIyMXdZVzU1VG1GdFpWVndaR0YwWlNJK1cwTnZiWEJoYm5rZ1RtRnRaVjA4TDJocFoyaHNhV2RvZEQ0OFluSWdMejRLUEdocFoyaHNhV2RvZENCamJHRnpjejBpWTI5dGNHRnVlVUZrWkhKbGMzTlZjR1JoZEdVaVBsdERiMjF3WVc1NUlFRmtaSEpsYzNOZFBDOW9hV2RvYkdsbmFIUStQR0p5SUM4K0NqeG9hV2RvYkdsbmFIUWdZMnhoYzNNOUltTnZiWEJoYm5sUWFHOXVaVlZ3WkdGMFpTSStXME52YlhCaGJua2dVR2h2Ym1WZFBDOW9hV2RvYkdsbmFIUStQR0p5SUM4K0NqeG9hV2RvYkdsbmFIUWdZMnhoYzNNOUltTnZiWEJoYm5sRmJXRnBiRlZ3WkdGMFpTSStXME52YlhCaGJua2dSVzFoYVd4ZFBDOW9hV2RvYkdsbmFIUStQR0p5SUM4K0NnPT0iCn0=

Terms of Service

Privacy Policy

Core Modal Title

Sorry, no results found

You Might Find These Articles Interesting

T
Please Check Your Email
We Will Be Following Up Shortly
*
*
*