cropper

Concierge Tax VIP

  • Home
  • Home
  • Menu
    • tax strategies for businesses
    • Business growth consultation
    • Fractional CFO for business growth
    • Growth Strategies
  • All Posts
  • Growth Strategies
  • Fractional CFO for business growth
  • tax strategies for businesses
  • Business growth consultation
March 26.2026
1 Minute Read

Tax Planning for Wealthy Taxpayers: Secrets to Save Big

Did you know that over 70% of wealthy individuals legally reduce their tax bills by tens or even hundreds of thousands each year through proactive tax planning? The right tax strategies can be the difference between keeping wealth or losing it to the ever-changing tax laws. If you think tax planning is just about filling out returns correctly, think again—there are complex, high-impact approaches that could redefine your financial future.

Unveiling the Secrets: Startling Statistics on Tax Planning for Wealthy Taxpayers

Tax planning for wealthy taxpayers isn’t just a matter of paperwork—it’s a competitive advantage. According to a 2023 survey by the National Association of Tax Professionals, nearly 80% of high-net-worth families work year-round with specialized financial advisors or tax planners to optimize their tax position. Furthermore, research shows that effective tax planning saves wealthy individuals between 15% and 45% on overall federal and state tax liabilities, depending on their asset structure and strategies used.

These statistics underline a crucial reality: for high-net-worth taxpayers, diligent tax planning isn’t optional—it’s essential for wealth preservation and growth. By leveraging advanced tax plan strategies, such as loss harvesting, real estate plays, and integrating business and personal finances, they remain several steps ahead of both tax law changes and market shifts. Ignoring these opportunities means potentially sacrificing millions over a lifetime.
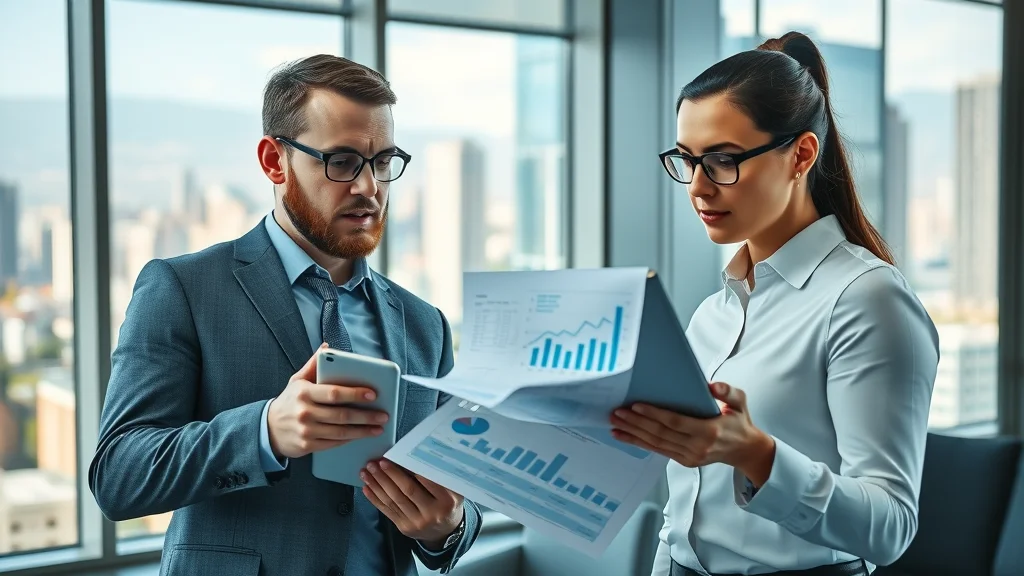
tax planning for wealthy taxpayers: Financial advisors analyzing tax planning data in a modern office, cityscape view.
“A proactive tax plan is the single greatest tool for preserving wealth.” — Leading Financial Advisor

What You'll Learn About Tax Planning for Wealthy Taxpayers

  • Essential tax strategies for high-net-worth individuals
  • Key tax law considerations affecting wealthy taxpayers
  • How a strategic tax plan integrates with comprehensive wealth management
  • Tactics for maximizing income tax and capital gains savings
  • Role of real estate, business ownership, and charitable giving in advanced tax planning

Understanding the Foundations: Tax Planning for Wealthy Taxpayers

Tax Plan vs. Tax Strategies: Setting the Right Approach

It’s important to distinguish between a tax plan and individual tax strategies. A tax plan is a holistic, long-term approach designed to optimize your tax position every year—across income tax, capital gains tax, estate tax, state tax, and more. Wealthy taxpayers often coordinate with a tax advisor or financial advisor to ensure that their plan evolves with changing tax laws, market opportunities, and personal circumstances. In contrast, tax strategies are specific methods—like Roth IRA conversions, real estate exchanges, or loss harvesting—applied as part of your overall plan. Without a unified tax plan, even the best tactics can fall short, failing to account for how tax law changes or income shifts impact your total tax burden and wealth management goals.

For affluent individuals, setting the right approach begins with understanding not just the available tools, but how those tools interact. Integrating tax planning into broader wealth management ensures that all parts of your financial world—investments, business interests, family goals—work together to keep your wealth compounding year after year.
tax plan foundation: Tax advisor presenting tax plan options to a client in an elegant conference room.

Overview of Wealth Management and Tax Planning Integration

For wealthy taxpayers, integrating wealth management and tax planning is vital. These two disciplines are deeply intertwined: every investment decision, estate plan update, or business restructuring triggers tax consequences. By working with experienced advisors, high-net-worth individuals can ensure portfolios are not just growing, but are optimized for after-tax returns and compliance with state and federal tax laws. This integration streamlines everything from charitable giving and trust establishment, to capital gain recognition and tax loss harvesting.

A holistic approach often includes regular reviews of financial plans, scenario analysis under different tax law changes, and diversified tax strategies that adjust for both market shifts and personal circumstances—maximizing the net benefit and protecting long-term assets. Ultimately, wealth management and tax planning together provide the backbone for sustainable, multigenerational wealth.

Income Tax and Capital Gains Tax Considerations

One of the most significant impacts on affluent individuals comes from income tax and capital gains tax. For those in higher tax brackets, investment income, capital gain events, and passive real estate profits can escalate tax bills quickly. Proactive tax planning for wealthy taxpayers includes techniques to shield income from excessive taxation (such as municipal bonds or tax-deferred accounts) and carefully time the realization of capital gains for optimal rates or in lower-income years.

Mindful management of tax brackets, leveraging tax deductions, and using loss harvesting during market downturns can meaningfully reduce your tax return each year. By balancing ordinary income, qualified dividends, and capital gain recognition, high-net-worth taxpayers can better predict—and control—their wealth trajectory.

Mastering Income Tax Strategies for Wealthy Taxpayers

Maximizing Taxable Income Efficiency

Efficiently managing taxable income lies at the core of advanced tax planning strategies for the wealthy. This involves not only minimizing taxable income through effective deductions and credits but also deferring income to future years or spreading income across family members in lower tax brackets. Working closely with a tax advisor helps pinpoint opportunities to maximize the timing and amount of deductions, capitalize on tax-deferred growth, and avoid pitfalls like the alternative minimum tax.

Additionally, structuring compensation through bonuses, equity, or performance-based awards can be optimized to align income with favorable tax years. Strategic use of retirement savings accounts, including deferred compensation plans and employer-sponsored 401(k)s, can further reduce current year taxable liability—all while accelerating long-term wealth building within your financial plan.
income tax strategy: Wealthy couple reviewing income tax optimization charts with a tax strategist in a sophisticated home office.

Loss Harvesting: Offset Gains and Save Big

Loss harvesting is a popular, effective tactic in tax planning for wealthy taxpayers. By strategically selling investments at a loss, high-net-worth investors can offset realized gains elsewhere in their portfolio—directly reducing their capital gains tax liability in a given year. In volatile or down markets, this can be especially powerful in protecting wealth. What's more, harvested losses that exceed gains can be carried forward to future tax years, creating a cushion against higher taxes for years to come.

When well-implemented, loss harvesting integrates seamlessly with other planning strategies, such as timing charitable gifts or real estate sales, making it a flexible and ongoing advantage. For best results, an annual review with a tax advisor or wealth manager ensures you capture losses efficiently and maintain compliance with wash sale rules.

Roth IRA Conversions for High-Income Individuals

Roth IRA conversions offer high-income taxpayers a unique opportunity: pay tax today at a potentially lower rate and shelter investment growth from future taxes. Many wealthy taxpayers hit contribution limits for traditional IRAs, but Roth conversions—moving funds from pre-tax accounts to Roth accounts—let you build a pool of tax-free income in retirement. This strategy is especially attractive when anticipating higher tax rates in coming years or following a year with lower-than-usual income.

Understanding the tax law nuances of Roth IRA conversions, including pro-rata rules and the impact on taxable income, is crucial to maximizing benefits and avoiding unintended consequences like pushing yourself into a higher tax bracket, losing deductions, or triggering Medicare surcharges. Expert planning ensures a smooth, tax-efficient conversion process that enhances your long-term financial security.
roth ira strategy: Wealthy individual reviewing Roth IRA options with a financial advisor in a luxury study.

Leveraging Savings Accounts and Tax-Free Growth Vehicles

Wealthy individuals often go beyond traditional accounts to leverage advanced savings accounts and tax-free growth vehicles. Health Savings Accounts (HSAs), 529 education savings plans, and cash-value life insurance all offer potent ways to grow assets with minimal or deferred taxes. By layering these with employer-sponsored plans and considering unique opportunities such as donor-advised funds, taxpayers can amplify both savings and tax benefits.

Coordination with tax advisors ensures contributions, withdrawals, and account structures align with current tax law, estate planning objectives, and wealth management strategies. Used wisely, these vehicles form a resilient component of a comprehensive financial plan, compounding advantages year over year.

Advanced Tax Strategies for Wealthy Taxpayers

Real Estate Planning: Minimizing Gains Tax and Maximizing Deductions

Real estate remains a cornerstone for wealth building and tax savings among the affluent. Strategies such as the 1031 exchange allow investors to defer paying capital gains tax when selling and reinvesting in qualifying properties. Optimizing depreciation schedules can result in significant deductions against rental and business income, reducing taxable income each year. Additionally, investing in Qualified Opportunity Zones offers not only initial deferrals but potential exclusion of gains if held long term.

Advanced real estate planning integrates each transaction—sale, acquisition, refinance—with broader tax plan objectives, considering the timing of gains, charitable gifts, and other planning strategies to minimize gains tax and maximize deductions.

  • 1031 exchange strategies
  • Optimal depreciation schedules
  • Qualified Opportunity Zones

real estate tax strategy: Experienced real estate investor analyzing gains tax strategies on a city rooftop.

Charitable Giving and Philanthropic Trusts

Philanthropy isn’t just about legacy—it’s a keystone of smart tax planning for wealthy taxpayers. Through direct charitable giving, donor-advised funds, and charitable trusts, high-net-worth taxpayers can claim significant deductions against both income and capital gains, while also reducing future estate tax burdens. CRTs (Charitable Remainder Trusts) and CLATs (Charitable Lead Annuity Trusts) grant income streams and flexibility for both donors and their causes.

Consulting a tax advisor to align philanthropic goals with tax and wealth management outcomes maximizes both immediate and long-term benefits. Well-crafted charitable strategies can efficiently transfer wealth to future generations while making a sustainable difference to the community.
charitable planning: Affluent donor and philanthropic advisor discuss trust strategies in advisory office.

Capital Gain and Capital Loss Strategies

Tactical management of capital gain and capital loss events is vital for minimizing tax liabilities. Beyond loss harvesting, timing asset sales across multiple tax years, using structured sales, and selectively realizing capital gains during lower income years can dramatically reduce overall taxes. Affluent taxpayers may also use installment sales or like-kind exchanges (where permitted by tax law) to spread out gains and minimize immediate tax impact.

Importantly, these strategies must be regularly reviewed and adjusted for evolving tax laws and shifting market conditions—yet another reason ongoing collaboration with a tax advisor is indispensable for wealthy individuals.

Navigating State Tax Complexities for High Net Worth Individuals

State taxes can be a major source of surprise and complexity in tax planning for wealthy taxpayers. Differences in state income tax, capital gains rates, estate tax, and even local tax codes mean that your state of residence, and where assets are located, can heavily influence your tax bill. For some, establishing domicile in a lower-tax or no-tax state is a crucial planning strategy; for others, it’s about coordinating state and local taxes to optimize overall liability.

Successfully navigating these complexities requires understanding not just current tax law, but anticipating legislative shifts and compliance risks. Working with advisors experienced in multi-state wealth management, state and local tax law, and cross-border planning ensures that affluent taxpayers remain compliant and efficient—no matter how their assets or life circumstances evolve.

Specialized Tax Planning for Business Owners and Entrepreneurs

Business Owner Tax Deductions and Structures

For the high-net-worth business owner, deliberate structuring is a cornerstone of tax planning—and it can deliver substantial savings. Key decisions include S-corp versus C-corp status, which have significant impacts on how business income is taxed; pass-through entity taxes and the Qualified Business Income (QBI) deduction; and methods for tax-efficient compensation. Proper coordination allows business owners to align earnings, distributions, and retirement plans for optimal after-tax growth.

Structuring business operations to maximize deductions, leverage available credits, and time expenses or asset purchases can keep more wealth compounding within the business. With changing tax laws, ongoing review with a tax advisor and business planning expert ensures each aspect of your tax plan reflects current rules and the owner’s long-term objectives.

  • S-corp vs. C-corp considerations
  • Pass-through entities and the Qualified Business Income deduction
  • Tax-efficient compensation strategies

business owner tax planning: Business owner and advisors mapping tax deduction and structure scenarios in a boardroom.

Succession Planning and Exit Strategies

Wealthy business owners must look beyond annual tax returns to prepare for eventual ownership transitions. Whether the goal is selling, passing the enterprise to heirs, or merging with another company, succession planning is pivotal to minimizing taxes, preserving legacy, and ensuring continuity. Key elements include gifting strategies, use of family limited partnerships, installment sales, and proper coordination of estate taxes and capital gains taxes in the exit process.

The optimal plan will be customized to the owner’s aspirations and family situation, requiring collaborative planning with attorneys, financial planners, and tax advisors. Such foresight ensures the value you’ve built isn’t eroded by unnecessary taxes at exit—and that your wealth management blueprint stays intact for future generations.

Wealth Management Synergy: Tax Planning for Wealthy Taxpayers

Working with a Financial Advisor or Tax Advisor

The ongoing support of a financial advisor or tax advisor is a hallmark of successful tax planning for wealthy taxpayers. Advisors serve as both strategists and gatekeepers, helping anticipate regulatory changes, optimize investment allocations, and coordinate between business, personal, and family accounts. Their expertise keeps your plan flexible, maximizing opportunities for tax savings as they arise throughout the year.

Establishing a long-term partnership with highly qualified professionals ensures that your tax and wealth management decisions remain aligned, even as your goals evolve or laws change. Choose advisors experienced in complex, high-net-worth scenarios for best results.
financial advisor collaboration: Elite financial advisor and affluent client reviewing tax projections in upmarket office.

Integrating Tax Planning Into Your Comprehensive Financial Plan

Truly effective tax planning doesn’t happen in a silo—it’s woven through your entire financial plan. Integrating estate planning, business interests, family governance, and philanthropy under one coordinated strategy ensures each decision supports your overall objectives and responds to changes in tax law, income streams, or asset values. Annual plan reviews, dynamic scenario analysis, and open communication between all advisors—tax, legal, and wealth management—are essential for ongoing optimization.

This approach gives wealthy taxpayers the agility and foresight needed not just to save on taxes, but to grow, preserve, and deploy wealth according to their highest priorities.

Essential Tax Law Changes and Their Impact on Tax Planning for Wealthy Taxpayers

Recent and Upcoming Tax Law Adjustments

Recent years have brought a host of adjustments to tax law, many targeting high-income earners through changes to income brackets, capital gains rates, qualified business deductions, and expanded reporting for foreign accounts and digital assets. Upcoming proposals, including possible changes to estate tax thresholds and stepped-up basis rules, promise further complexity.

Staying current with tax law changes is crucial for wealthy taxpayers to avoid unpleasant surprises and to seize new tax benefit opportunities as they arise. Proactive reviews with a tax advisor ensure your plan accounts for both confirmed and anticipated regulatory shifts, keeping your wealth protected and growing.
tax law changes: Finance analysts discussing tax law updates in a modern legal office.

Compliance Pitfalls to Avoid in Advanced Tax Strategies

While advanced tax strategies offer major advantages, they can also trigger scrutiny from the IRS if not executed properly. Non-compliance risks include missed filings, incorrect structuring of trusts or business entities, and misapplication of deductions or credits. Oversights may result in significant penalties, loss of tax benefit, or even legal challenges—especially as the IRS targets aggressive tactics among wealthy taxpayers.

Regular compliance checks, documentation, and working exclusively with experienced advisors significantly reduce these risks. Adhering strictly to the ever-evolving state and federal tax laws is pivotal for protecting both your wealth and reputation.

Tables: Comparisons of Tax Planning Strategies for Wealthy Taxpayers

Strategy Tax Savings Impact Complexity Risk Level
Loss Harvesting High Moderate Low
Roth IRA Conversions Medium to High (Long-term) Moderate Moderate
1031 Real Estate Exchange High (Capital Gains Deferral) High Moderate
Charitable Trusts Medium High Low
Pass-Through Entity Structuring Medium High Moderate
State Residency Repositioning Medium Moderate High (Audit Risk)

Quotes from Leading Financial Advisors on Tax Planning for Wealthy Taxpayers

"Effective tax planning for wealthy taxpayers requires advanced foresight and the ability to adapt to changing regulations." — Senior Wealth Management Expert
"The synergy of a custom tax plan and prudent wealth management is the foundation of real wealth preservation for affluent individuals." — Noted Tax Advisor

Lists: Quick Tips for Tax Planning for Wealthy Taxpayers

  1. Review your tax plan annually with a financial or tax advisor
  2. Strategically realize capital gains and losses each year
  3. Leverage charitable giving as both a legacy and deduction tool
  4. Utilize advanced savings accounts for tax-free growth
  5. Continuously monitor changes in tax law that impact wealthy taxpayers

People Also Ask: Key Questions on Tax Planning for Wealthy Taxpayers

What is the most effective tax planning strategy for high-net-worth individuals?

The most effective tax planning strategy for high-net-worth individuals is having a customized, comprehensive tax plan that integrates multiple tactics—including income tax deferral, loss harvesting, charitable trusts, optimal real estate investments, and advanced savings accounts—tailored to personal goals, asset mix, and changing tax laws. Ongoing collaboration with advisors and regular plan updates is key to maximizing returns and minimizing liabilities.

How does real estate play a role in tax planning for wealthy taxpayers?

Real estate investing offers wealthy taxpayers powerful avenues for tax savings, such as deferring gains through 1031 exchanges, maximizing deductions via depreciation, and leveraging Opportunity Zones for substantial long-term tax benefit. Coordinated real estate strategies can reduce both income and capital gains tax, enable efficient legacy planning, and boost after-tax returns over time.

Are there risks in aggressive tax strategies for wealthy taxpayers?

Yes, aggressive tax strategies can trigger IRS scrutiny, lead to missed filings or misapplied deductions, and result in penalties, back taxes, or legal challenges. The risk increases with more complex maneuvers like offshore trusts, state residency changes, or rapidly evolving digital assets. Strict compliance and professional oversight are critical to staying within the boundaries of current tax law and maintaining wealth protection.

How often should wealthy taxpayers review their tax plan?

Wealthy taxpayers should review their tax plan at least annually, and immediately following any significant life events, tax law changes, or business or investment opportunities. Annual reviews ensure strategies remain aligned with financial goals, respond to legislative updates, and capture emerging tax-saving possibilities.

FAQs About Tax Planning for Wealthy Taxpayers

What is loss harvesting, and how does it work?

Loss harvesting involves selling losing investments to offset realized gains from appreciated assets, thus reducing your capital gains tax that year. Unused losses can be rolled into future years. It requires careful documentation and adherence to wash sale rules to ensure compliance and tax benefit realization.

Do Roth IRA conversions make sense for high-income taxpayers today?

Roth IRA conversions can make sense for high-income taxpayers who expect to face higher income taxes in the future, want to build tax-free retirement income, or have a uniquely low-income year. They require careful planning to avoid overstepping into higher tax brackets or losing key deductions.

How does estate planning intersect with tax planning for wealthy taxpayers?

Estate planning and tax planning are closely linked for wealthy taxpayers. Strategic gifting, trust establishment, and asset transfers can reduce overall estate taxes, provide for heirs in a tax-efficient manner, and integrate seamlessly with a broader financial plan to preserve multigenerational wealth.

Key Takeaways: Strategic Tax Planning for Wealthy Taxpayers

  • Tax planning is crucial for managing and preserving substantial wealth.
  • Leveraging multiple strategies maximizes tax efficiency and protection.
  • Collaboration with professional advisors enhances plan effectiveness.
  • Staying updated on tax law changes helps maintain compliance and optimization.

Next Steps

Ready to unlock even more power from your wealth? Give us a call @ 1. 877. 776. 6829 or visit our website Conciergetax. vip today for a personalized consultation and see how expert tax planning can help you save big.

Sources

  • https://www.irs.gov/newsroom/tax-tips-for-high-income-taxpayers – IRS: Tax Tips for High-Income Taxpayers
  • https://www.natptax.com/TaxKnowledgeCenter/Pages/Resources/Tax-Education-for-High-Income.aspx – National Association of Tax Professionals: Tax Education for High-Income
  • https://www.kiplinger.com/taxes/tax-planning-for-the-wealthy – Kiplinger: Tax Planning for the Wealthy
  • https://www.cnbc.com/select/tax-strategies-for-high-net-worth-individuals/ – CNBC: Tax Strategies for High Net Worth Individuals

For high-net-worth individuals seeking to optimize their tax strategies, the article “7 Effective Tax Optimization Strategies for High-Net-Worth Individuals” offers valuable insights into methods such as maximizing contributions to tax-advantaged accounts, utilizing charitable giving, and implementing tax-efficient investment strategies. (globaladvisorgroup. com) Additionally, “Tax Planning Strategies for High Net Worth Individuals” provides a comprehensive overview of approaches like leveraging real estate investments and optimizing business structures to minimize tax liabilities. (danerwealth. com) If you’re serious about preserving and growing your wealth, these resources will equip you with the knowledge to implement effective tax planning strategies tailored to your financial goals.
tax strategies for businesses

17 Views

0 Comments

Write A Comment

*
*
Please complete the captcha to submit your comment.
Related Posts All Posts
09.23.2026

Discover the Hidden Power of Legal Tax Mitigation Strategies Today

Imagine sitting at your kitchen table, sipping coffee on a sunny morning, and realizing your tax worries are melting away—not because you made money vanish, but because you understood and used the rules to your advantage. With the right legal tax mitigation strategies, everyday people and small business owners can transform tax season from a stress-inducing ordeal into a calculated step toward financial success. This guide uncovers how simple, compliant choices can help you keep more of what you earn. Unveiling Legal Tax Mitigation Strategies for Financial Peace of Mind The heart of effective tax planning isn’t about dodging the law—it’s about maximizing your opportunities within it. Legal tax mitigation strategies can make a significant difference by reducing your income tax liabilities, growing your wealth for retirement, and protecting your investments. Whether you’re managing a household budget or running a small business, understanding the tools available—such as IRAs, savings accounts, and credits—gives you power over your money. By familiarizing yourself with key topics like the differences between a Roth IRA and a Traditional IRA, understanding capital gains taxes, and tapping into the expertise of a tax advisor, you make each tax year a smoother process. Let’s dive into the transformative basics and practical steps anyone can take—without becoming an accountant. An everyday scenario: Navigating taxes with confidence Take Sarah and Mike, who once found April’s tax deadline overwhelming. By using a few essential legal tax mitigation strategies—like contributing to a traditional IRA and tracking allowable itemized deductions—they now approach tax time with planning, not panic. Their story is common: gaining knowledge, making a plan, and turning anxiety into empowerment. With some consistency and a little help, you can do the same. As you read on, you’ll discover not just how to save on taxes, but how to safely and confidently integrate these lessons into your everyday financial decisions. What You'll Learn About Legal Tax Mitigation Strategies The basics of legal tax mitigation strategies and their importance Essential tax planning concepts everyone should know Popular strategies for individuals and small businesses Key differences between Roth IRA and Traditional IRA for tax planning How capital gains and savings accounts factor into your approach When to consult a tax advisor Understanding Legal Tax Mitigation Strategies: Foundations and Importance Defining Legal Tax Mitigation Strategies Simply put, legal tax mitigation strategies are techniques used to minimize the amount of taxes owed through methods permitted by tax law. These include using available deductions, contributing to certain savings or investment accounts, carefully timing when you receive income or sell assets, and selecting the right retirement plan. Unlike illegal tactics that try to evade taxes, these practices are not only approved, but encouraged by the government to incentivize saving, investing, and charitable giving. For example, by maximizing permitted IRA and 401(k) contributions, tracking itemized deductions, and managing capital gains through strategic sales, taxpayers can align with both the spirit and the letter of the law. These strategies are tools—available to anyone willing to plan ahead. Why Everyone Needs to Know Legal Tax Mitigation Strategies You don’t need to be a millionaire or run a large company to benefit from tax planning. Anyone earning income—whether through a job, running a small business, or investing in real estate—can make small, legal adjustments that add up over time. By learning and applying these strategies early, you can lower your effective tax rate, keep more of your gross income, and gain more control over your financial future. Knowledge is key: the tax code may seem overwhelming, but a few well-understood basics can lead to years of savings. Whether you’re claiming the standard deduction or maximizing your health plan contributions, every bit counts—especially as laws change and new tax-saving opportunities emerge. When in doubt, a reputable tax advisor can guide you confidently through the process. Core Concepts in Tax Planning for Effective Legal Tax Mitigation Strategies Building Tax Planning Into Your Financial Routine Effective tax planning isn’t a once-a-year scramble. It’s about integrating smart habits into your day-to-day financial life—tracking expenses, understanding when to use itemized deductions over the standard deduction, and ensuring your adjusted gross income stays within optimal tax brackets. Consistency is crucial: reviewing your income tax choices with each big milestone (a new job, home purchase, or child’s birth) keeps you prepared. For instance, if you receive a year-end bonus, investing it in a retirement plan like a 401(k) or IRA may reduce your current year’s tax burden. Keeping records of charitable donations and medical expenses can also maximize eligible itemized deductions. Simple steps—done throughout the year—build a strong foundation for tax-efficient living. Leveraging Qualified Retirement Plans for Tax Benefits Qualified retirement plans offer two major tax advantages: upfront deductions and long-term tax-free growth. The traditional IRA lets you lower your adjusted gross income now by making pre-tax contributions, reducing your current-year taxable income. In contrast, the Roth IRA accepts after-tax dollars, but rewards you later with tax-free withdrawals in retirement. Choosing the right account depends on your current and expected tax bracket. Contributing to a Traditional IRA: Reduce current taxable income through pre-tax contributions. Opting for a Roth IRA: Pay taxes now for tax-free growth and withdrawals in retirement. Both options can be part of a broad tax planning strategy. Many savers opt to split contributions, hedging future tax law changes and offering themselves more flexibility in retirement. Exploring Account Types: Savings Accounts, IRAs, and More Using Savings Accounts for Tax-Efficient Growth While basic savings accounts don’t offer the same immediate deductions as IRAs, they remain valuable for building emergency funds and achieving short-term goals. Interest earned on these accounts is typically taxed as ordinary income, and while rates are modest, keeping a portion of your portfolio liquid and safe is crucial for weathering the unexpected. However, some health plans like HSAs (Health Savings Accounts) and 529 college savings plans amplify your tax savings beyond basic accounts—offering tax-deferred or tax-free growth for qualified expenses. Integrating a mix of account types creates balance: safety for today, and tax-efficient growth for tomorrow. Traditional IRA vs. Roth IRA: Which Is Best for Legal Tax Mitigation Strategies? Choosing between a traditional IRA and a Roth IRA is a core tax planning decision. Each has distinct benefits—and the right choice depends on whether you need tax relief today or are planning for a lower tax rate in retirement. We break down the essentials: Roth IRA Traditional IRA No deduction but tax-free withdrawals Contributions may be tax-deductible Taxes paid upfront; no taxes later Taxes paid on withdrawal No RMDs Required minimum distributions (RMDs) Ideal if you expect higher taxes in the future Beneficial for those anticipating lower income in retirement Evaluate your future needs, current tax bracket, and consult with a tax advisor for a tailored strategy. "The best time to start thinking about taxes is before the tax year begins. Early planning puts you in control." — Tax Advisor Insight Capital Gains: Minimizing Taxes on Investments with Legal Tax Mitigation Strategies Short-Term vs. Long-Term Capital Gains in Tax Planning Taxes on investment profits—known as capital gains—vary based on how long you hold your asset. Short-term capital gains, from assets held less than a year, are taxed as ordinary income at your regular rate. Long-term capital gains, from sales after more than a year, usually benefit from a lower capital gains tax rate. This difference can be significant, impacting your after-tax returns. Smart investors plan sales to maximize long-term gains, avoid unnecessary gains tax, and use strategies like loss harvesting to offset profits with losses. These distinctions matter even more in years when you sell large real estate holdings, stocks, or other major investments. Smart Strategies for Reducing Capital Gains Taxes Reducing your capital gains taxes isn’t about avoiding your obligations—it’s about using the flexibility tax law provides: Harvest investment losses to offset gains Utilize tax-exempt investment accounts Time asset sales for optimal tax years For example, selling lower-performing stocks to offset winnings can blunt the income tax impact in a volatile market year. Considerations like these are why proactive tax planning pays off not just for you, but for your entire family’s financial outlook. Federal Tax Law and Legal Tax Mitigation Strategies Understanding Federal Tax Provisions You Can Use Current federal tax laws offer plenty of tools for taxpayers seeking legal reductions. The standard deduction makes filing easy for most, but if your itemized deductions—like charitable deductions or state and local taxes—exceed it, you may save more by itemizing. Recognizing which credits you qualify for (education, energy-saving home upgrades, child tax credits) can also make a notable difference. Many changes to tax law and tax rates happen each year, so reviewing your options at least annually—and when your personal situation changes—is advisable. Always consider your adjusted gross income, filing status, and potential for new deductions or credits. Staying current can maximize your legal tax savings. The Role of a Tax Advisor in Legal Tax Mitigation Strategies A qualified tax advisor doesn’t just file forms—they guide your decisions and help you use every available legal strategy. These professionals understand evolving federal tax laws and can customize a tax planning approach for you or your business. With the right advisor, you’ll avoid costly errors, take full advantage of charitable deductions, and navigate complex topics like the IRS 7 year rule or retirement plan distributions. If your finances are complicated—perhaps involving multiple income sources, investment properties, or small business interests—a tax advisor is invaluable. They provide peace of mind and help you prepare for both current and future tax years. Legal Tax Mitigation Strategies for Small Business Owners Key Opportunities in Tax Planning for Businesses Small business owners can unlock a different set of legal tax mitigation strategies. Beyond maximizing retirement plan contributions, business owners can defer income to a future tax year, claim a broad range of business expenses, and use specialized accounts, like HSAs, for tax-advantaged savings. Proper tax planning also includes staying compliant with state and local taxes, managing inventory for optimal capital gains, and tracking qualified expenses for maximum deduction. Working with an experienced tax advisor ensures you don’t miss hidden opportunities, like the qualified business income deduction or retirement matching programs, creating powerful tools for business growth and personal savings alike. Popular Legal Tax Mitigation Strategies: A Quick List Maximize retirement plan contributions (Traditional IRA, Roth IRA, 401(k)) Defer income where possible Harvest capital losses Contribute to tax-advantaged accounts (HSAs, 529 plans) Claim all entitled credits and deductions Answers to Popular Legal Tax Mitigation Strategies Questions What are the best tax mitigation strategies? The most effective legal tax mitigation strategies involve consistent planning—contributing to IRAs and retirement accounts for deductions and future security, timing asset sales to maximize long-term capital gains tax preferences, and itemizing deductions when they exceed the standard deduction. Use tax-advantaged accounts like HSAs and 529s, and always stay informed about credits or changes to tax law that could work in your favor. Can I legally opt out of paying taxes? No, U. S. tax law requires all eligible individuals and businesses to pay federal tax on their income. However, you can use legal tax mitigation strategies to reduce your liability—such as contributing to retirement plans, utilizing credits, or claiming allowable itemized deductions—but total avoidance is illegal and can result in significant penalties. How can I legally reduce my income tax? Lowering your income tax legally comes down to maximizing deductions and credits (such as for dependents, education, or charitable donations), investing in retirement accounts like a Roth IRA or traditional IRA, and planning the timing of income or asset sales. Consulting a tax advisor ensures you navigate these opportunities correctly for your unique situation. What is the IRS 7 year rule? The IRS “7 year rule” generally refers to the recommended period for keeping back tax records and documentation, especially if you claim loss deductions for worthless securities or bad debt. While three years is often enough for standard returns, certain situations warrant holding onto records for up to seven years to be safe. Quick FAQs: Legal Tax Mitigation Strategies Is it legal to use deductions to lower taxes? Are Roth IRAs better for young savers? Do tax mitigation strategies work for business owners? How often should I review my tax plan? What role does a tax advisor play? Key Takeaways on Legal Tax Mitigation Strategies Legal tax mitigation strategies are essential tools for reducing tax liability and achieving peace of mind. Early and consistent tax planning leads to better outcomes. Retirement accounts such as Roth IRA and Traditional IRA are common vehicles. A knowledgeable tax advisor can help you navigate complexities and take advantage of legal opportunities. Expert tax advisor explains step-by-step legal tax mitigation strategies using diagrams and real-life examples in a 2-minute overview, shot in a modern office setting. Need Help With Legal Tax Mitigation Strategies? Give us a call @ 1. 877. 776. 6829 or visit our website Conciergetax. vip today for expert guidance tailored to your needs. Conclusion Incorporating legal tax mitigation strategies is your pathway to greater financial confidence, security, and long-term success. Start planning now, consult a trusted advisor, and turn your tax concerns into opportunities for growth. Sources https://www.fidelity.com/learning-center/personal-finance/how-to-reduce-taxable-income - 9 ways to potentially reduce your taxable incomehttps://www.ml.com/articles/tax-tips-that-could-save-you-money.html - 10 Tax Tips That Could Save You Money on Your Taxeshttps://www.fidelitycharitable.org/articles/six-tax-strategies-you-should-know.html - Six Tax Strategies You Should Knowhttps://www.edelmanfinancialengines.com/education/tax/14-tax-saving-strategies/ - 14 Tax Saving Strategies to Minimize Your Expenseshttps://www.fidelity.com/learning-center/personal-finance/tax-moves - Key tax moves for 2026https://privatebank.jpmorgan.com/nam/en/insights/markets-and-investing/ideas-and-insights/act-now-14-ways-to-lower-your-tax-bill - Act now: 14 ways to lower your tax billhttps://www.modernfamilyfinance.com/beyond-the-basics-tax-strategies-for-high-income-earners/ - Beyond the Basics: Tax strategies for High Income Earnershttps://www.morganstanley.com/articles/how-to-protect-your-income - 7 Steps That May Reduce Taxes on Your Income and ...

09.10.2026

What Most People Don’t Know About Cryptocurrency Taxes Demystified

Imagine the excitement of making your first crypto trade—only to discover there are tax rules and filing requirements you hadn’t planned for. Many new investors and even seasoned traders overlook key details that can complicate tax season and put you at risk of IRS scrutiny. This concise guide to cryptocurrency taxes demystified gives you the essential info and best practices to help you avoid costly mistakes and stay compliant.Shedding Light on Cryptocurrency Taxes DemystifiedImagine making your first crypto trade and suddenly hearing about taxes you didn’t expect—this guide explains why that happens and what you can do about it.Cryptocurrency taxes demystified is all about making the complex world of crypto tax obligations clear and approachable. Most people are caught off guard when they learn their digital asset activity—like trading, selling, or even spending crypto—often triggers tax consequences, even though “holding” crypto is not taxable. In this section, you’ll discover why crypto taxes matter, how the IRS views digital assets, and the importance of proper record keeping and tax reporting. Whether you’re a new investor or already trading different coins, understanding these rules is crucial to avoiding penalties, missed deductions, or audit headaches. Cryptocurrency is exciting, but when it comes to compliance, the IRS treats digital currency transactions much like those of stocks or other investments. With the growing scrutiny from regulators, being proactive is your best strategy.What You'll Learn About Cryptocurrency Taxes DemystifiedThe basics of crypto taxWhat counts as a taxable eventHow capital gains and losses workEssential tax forms and reporting tipsCommon crypto tax misconceptionsUnderstanding Crypto Taxes: How Cryptocurrency Taxes Demystified Helps You Stay CompliantGrasping cryptocurrency taxes demystified begins with knowing which actions are taxable and the different ways digital assets are reported to the IRS. Crypto tax rules classify most currency transactions—beyond just selling for cash—as potential taxable events. These requirements apply to gains and losses from trading coins, using crypto for goods or services, and even earning coins from work, mining, or staking. Staying compliant means understanding IRS requirements, tracking each transaction, and accurately reporting the capital gain or loss on your tax return. The IRS has increased its focus on tax compliance for digital assets and issues notices requiring clear and complete records of every purchase, sale, and trade. By staying up to date with these regulations, you can avoid the risk of penalties and leverage deductions for losses or expenses where applicable.What Is Considered a Taxable Event in Crypto Taxes?BuyingSellingTrading different coinsUsing crypto for purchasesEarning crypto as incomeA taxable event is any action that the IRS considers as creating a gain or loss for tax purposes, and this is essential to understanding cryptocurrency taxes demystified. For crypto assets, this includes selling crypto for cash, trading one type of coin for another, using tokens to pay for goods or services, and earning coins through income-generating activities like mining or staking. Importantly, simply buying or holding crypto does not count as taxable until you sell or otherwise dispose of it. Recognizing all forms of taxable currency transactions helps ensure you're tracking activity instead of missing key events that need to be included in your tax report.For those just starting out, missing a taxable event—like swapping Bitcoin for Ethereum—could mean inaccurate records come tax time. Using crypto tax software or working with a tax advisor can help you properly classify every potential taxable event. The key takeaway: knowing when your actions trigger a tax liability forms the foundation to stay on the right side of crypto tax law.Explaining Capital Gain and Capital Gains TaxDefinition of capital gain and capital gains taxDifference between short-term and long-term capital gainsReal-world examplesYour capital gain is the profit when you sell a crypto asset for more than you paid for it (your cost basis). When you dispose of digital assets—by selling or trading, for example—you must calculate your gain or loss based on the current fair market value compared to your initial purchase price. The capital gains tax applies to this profit. There are two main types: short-term capital gains (for assets held less than a year, taxed as ordinary income) and long-term capital gains (for assets held longer than a year, taxed at a potentially lower rate).For instance, if you bought Bitcoin at $4,000 and sold it at $6,500 after holding it for 16 months, the $2,500 profit is a long-term capital gain and may be taxed at a reduced tax rate. However, if you made that sale after only five months, it’s a short-term capital gain, usually taxed at the same rate as your salary or wages. Understanding these distinctions protects you from under- or over-reporting and helps maximize potential savings when properly reporting on your tax form.Understanding Gains and Losses for Crypto Taxes DemystifiedHow to track gains and losses on cryptocurrencyTax rules for reporting bothTracking gains and losses from crypto activity is one of the most important—and challenging—parts of compliant tax reporting. Every sale or trade of digital assets must be recorded with details: purchase price, sale price, date, and the specific asset involved. This enables you to determine the net gain or loss for each transaction, then total them for your annual return. Accurate records let you report capital gains and losses on IRS forms 8949 and Schedule D. Software tools and spreadsheet templates make it easier to track, categorize, and export this information for your tax return.By maintaining well-organized records, you can fully claim allowable capital losses which may offset gains elsewhere, reducing your total tax bill. But missing even a few transactions—or mixing up short-term and long-term holdings—can result in an incorrect tax report and potential IRS issues. The bottom line: don’t overlook losses, and always double-check your records before filing.Cost Basis Calculation for Cryptocurrency Taxes DemystifiedAt the heart of cryptocurrency taxes demystified is the concept of cost basis. Cost basis is the original value of an asset for tax purposes, typically what you paid plus any fees, and is critical when calculating capital gains and losses. The IRS lets you choose between different methods—like FIFO (First In, First Out), LIFO (Last In, First Out), or Specific Identification—for tracking which coins are being sold or traded. The method you choose affects the size of your gain or loss and, consequently, your tax obligation. If your records are incomplete or the chosen calculation method is inconsistent, the IRS may challenge your reported figures.What Is Cost Basis and Why Does It Matter for Crypto Tax?Definition of cost basisMethods for calculating cost basisImpact on capital gains and lossesCost basis determines your real profit or loss and is fundamental for cryptocurrency taxes demystified. Think of it as your purchase price—including any transaction fees you paid. When you sell, trade, or spend your coins, subtract your cost basis from the fair market value (FMV) at the time of sale to find your gain or loss. There are several acceptable ways to calculate cost basis: FIFO (first coins bought are the first sold), LIFO (the most recent coins bought are the first sold), and Specific Identification, which lets you assign particular coins with their purchase price to each sale.Choosing a cost basis method and applying it consistently to your records helps ensure you report the right amount of capital gain or loss and avoid IRS penalties. This process can be complex if you have lots of currency transactions or coins purchased at different times and prices. Crypto tax software or professional advice can make tracking and calculation easier, lowering your risk of audits or underreported gains.Tax Forms and Reporting: Navigating Cryptocurrency Taxes DemystifiedWhen tax season rolls around, being familiar with the correct tax forms for cryptocurrency transactions is key. The IRS has standardized forms used for reporting capital gains and losses, income from crypto, and special scenarios like airdrops. Proper tax reporting ensures your crypto activity is legally documented, reducing risk and giving you peace of mind. Leveraging these forms also lets you capture allowable capital loss deductions, maximizing your potential refund or lowering your overall tax bill. Knowing which forms apply based on your activity—selling, trading, earning—is fundamental for a smooth tax experience.Key Crypto Tax Forms You’ll Need8949Schedule D1040Other common formsForm 8949 is where you list all capital gains and losses from selling or trading crypto. These entries are then summarized on Schedule D, which is included as part of your annual 1040 federal tax return. If you earned income—such as from mining, staking, or payment for services—report it as ordinary income on form 1040 or a business schedule. Other tax forms may be required in special circumstances, like reporting foreign accounts holding crypto. Staying informed about these requirements ensures your tax return reflects your digital asset activity completely and correctly.Filing Tips for Cryptocurrency Taxes DemystifiedKeeping detailed recordsUsing crypto tax softwareWhen to seek professional guidanceAccurate filing is all about preparation and diligence. Start by keeping thorough records of every transaction including dates, amounts, counterparties, and the fair market value at the time of each trade. While some exchanges offer transaction histories, don’t rely only on platform reports—check for missing data, and supplement as needed. Crypto tax software can automate much of the data collection, cost basis calculation, and tax report generation, making life easier at tax time. If your portfolio is complex, involves multiple wallets or exchanges, or you’re unsure about IRS rules, seeking help from a crypto tax advisor or financial professional can save time, money, and headaches. A trusted expert will also keep you up to date with IRS notice changes, avoiding improper or late filings.Special Cases: Crypto Taxes Demystified for Hard Forks and AirdropsHow hard forks are taxedTax treatment of airdropped coinsSpecial events like hard forks and airdrops are unique to digital assets and bring their own tax implications. A hard fork happens when a blockchain splits and you receive new coins as a result. According to IRS guidance, this is generally treated as ordinary income equal to the fair market value of the new coins received at the time they’re accessible.Similarly, if you receive airdropped coins, their fair market value at receipt is recognized as taxable income and reported on your tax return. Both cases trigger tax events regardless of whether you sell or hold the new coins—so keeping close records is crucial. If you later sell or exchange those coins, that becomes a separate taxable event, with cost basis set at the FMV upon receipt.Income Tax and Cryptocurrency Taxes DemystifiedNot all crypto taxes involve capital gains—some crypto income is treated as regular ordinary income instead. If you earn crypto through mining, staking, or as payment for services, these amounts are taxed as income at their fair market value when received. Then, if you later sell or trade those coins, the usual capital gain or loss rules apply based on their value when you acquired them. This dual taxation structure—income tax at collection, capital gains at disposal—makes clear records and separation of events vital.When Is Crypto Treated as Income for Tax Purposes?MiningStakingPayment for servicesAny time you acquire digital assets through mining, staking, or as direct payment for goods or services, the IRS considers the fair market value at receipt to be taxable income. This differs from simply buying or holding coins, which isn’t taxed until you sell. These amounts are reported as part of your 1040 income tax return, and are taxed at ordinary income tax rates. Keeping track of the value when you receive coins is essential for both your income tax and setting the correct cost basis if you later sell those assets.For example, miners who receive crypto as a block reward must report the current market price as income even if they don’t immediately convert it to cash. Professionals who accept digital asset payments for services must also report the dollar value received as income. This distinction between earning and investing is fundamental for compliance.Tax Rate Considerations for Crypto Taxes DemystifiedHow tax rates apply to crypto income and gainsIntroduction to relevant bracketsThe tax rate that applies to your crypto depends on the type of transaction. Income from mining, staking, or business services is taxed at your ordinary income tax rate, which rises with your overall income and can hit higher federal tax brackets. In contrast, capital gains are split into short-term (taxed as ordinary income if held less than a year) and long-term (typically taxed at 0%, 15%, or 20% depending on your total income). Knowing which bracket you fall into and planning sales accordingly can help minimize your overall crypto tax liability.It’s also important to stay current with IRS guidelines, as rates and brackets are periodically reviewed and updated. Specialized circumstances—such as large one-time sales or a combination of crypto income types—may call for working with a tax advisor to ensure you’re taking advantage of all available deductions and credits.Common Misconceptions About Cryptocurrency Taxes DemystifiedCrypto is anonymous and untaxedSmall transactions don’t need reportingOnly cashing out triggers taxesMany mistakenly believe that crypto is either anonymous or goes under the IRS radar, but recent IRS notice campaigns and platform reporting requirements prove otherwise. No matter the size, any taxable transaction—even a cup of coffee bought with Bitcoin—should be included in your tax report. Another common myth is that only “cashing out” to fiat triggers tax; in reality, trades, exchanges, and even earning coins through rewards or work all count as taxable events. Misinformation or misunderstanding these nuances leads to underreporting, penalties, and missed tax planning opportunities.Strategies to Stay Ahead on Cryptocurrency Taxes DemystifiedOrganizing records throughout the yearConsidering tax-loss harvestingStaying updated on tax law changesProactive planning is the best way to simplify cryptocurrency taxes demystified. Start by logging every transaction as it happens, including deposits, withdrawals, trades, and airdrops. Don’t rely on exchanges to keep perfect records—backup your own and audit periodically. Consider tax-loss harvesting: if you have coins that have declined in value, you may be able to use those losses to offset gains elsewhere for the same year. And with tax law for digital assets evolving fast, subscribe to updates from the IRS or rely on a professional to keep your approach current. Consistency and diligence now can save time, stress, and money at tax season.Table: Comparison of Tax Treatment for Different Crypto ActivitiesActivityTaxableExample Tax FormBuyingNo-SellingYes8949, Schedule DTradingYes8949, Schedule DEarning IncomeYes1040Hard Fork/AirdropYes1040Quotes from Tax Experts on Cryptocurrency Taxes Demystified"Understanding your cost basis and accurately tracking your trades are crucial steps to avoid headaches and penalties from the IRS." – Crypto Tax AdvisorLists: Best Practices for Filing Cryptocurrency Taxes DemystifiedLog every transactionDon’t rely solely on exchanges for recordsDouble-check all tax forms before submittingSet aside funds for taxes owedPeople Also Ask About Cryptocurrency Taxes DemystifiedAt what point do I have to pay taxes on crypto?You typically owe taxes when you realize a gain—such as selling, exchanging, or using crypto for purchases. Simply holding isn’t taxable.Will you be taxed for a $1000 in crypto profit?Yes, a $1,000 profit from selling or exchanging crypto is considered a taxable gain and must be reported on your tax return.How much capital gains tax will I pay on $300,000?The rate depends on your holding period and tax bracket. Long-term capital gains (over one year) are taxed at a lower rate compared to short-term gains (under a year), which are taxed as ordinary income.How will crypto be taxed in 2026?Although tax laws can change, most experts predict continued scrutiny, with more detailed reporting requirements and possible adjustments to rates or brackets.FAQs: Quick Answers about Cryptocurrency Taxes DemystifiedDo I need to pay tax if I never sold my crypto? (No, only realized gains are taxable.)Are crypto gifts taxable? (Usually not for the recipient, but the giver may need to file.)Can I deduct trading losses? (Yes, up to certain IRS limits.)Key Takeaways from Cryptocurrency Taxes DemystifiedAlmost every cryptocurrency transaction can be a taxable eventAccurate record keeping is keySeek informed guidance to avoid mistakesReady for Tax Season? Expert Assistance for Cryptocurrency Taxes DemystifiedHave questions about navigating crypto taxes? Give us a call @ 1.877.776.6829 or visit our website Conciergetax.vip today for tailored advice.ConclusionStay proactive: log every transaction, double-check your records, and consult an expert when needed to make cryptocurrency taxes demystified a breeze.Sourceshttps://www.fidelity.com/learning-center/trading-investing/crypto/crypto-taxes-explained - Crypto taxes explained | Fidelityhttps://www.morganstanley.com/insights/articles/crypto-taxes-investor-guide - Crypto Taxes, Explained: Wallets, Stocks, Funds and Futureshttps://ltaxconsulting.com/blog/crypto-tax-2025-demystified-everything-you-need-to-know-to-stay-compliant - Crypto Tax 2025 Demystified: Everything You Need to ...https://turbotax.intuit.com/tax-tips/investments-and-taxes/your-cryptocurrency-tax-guide/L4k3xiFjB - Your Crypto Tax Guide - TurboTax - Intuithttps://coinledger.io/guides/crypto-tax - Crypto Taxes: The Complete Guide (2026)https://bipartisanpolicy.org/issue-brief/how-is-cryptocurrency-taxed-current-rules-and-outstanding-questions/ - How Is Cryptocurrency Taxed? Current Rules and ...

08.27.2026

Don't Make This Costly Mistake in Selling Your Business? Cases!

Imagine this: after dedicated years building your small business, you’re ready to turn the page. You find a potential buyer, you think your business is worth more—but suddenly, a missing document, a misunderstood tax implication, or a rushed valuation throws a wrench in the sale process. For many business owners, selling your business? can be a once-in-a-lifetime event, so getting it right is critical. Let’s explore simple steps and tips so you don’t stumble on these costly mistakes when it comes time to sell.Why Selling Your Business? Is a Critical Decision for Every Business OwnerSelling your business? is one of the most significant decisions a business owner can make. It signals not just a financial transaction, but a major life and career transition. For small business owners, the stakes are high—your sale price, financial future, and legacy are on the line. Navigating the business sale process with confidence requires more than just listing your business for sale. You need a firm grasp of business valuation, tax implications, and the essential legal documents to keep your sale on track.The impact of a business sale ripples far beyond your immediate financial gain. You’ll face decisions around when to sell, how to prepare your small business for sale, and how to maximize your outcome while avoiding common missteps. By understanding what professional business brokers look for and leveraging sound advice, business owners can avoid delays, maximize sale price, and ensure a smooth handover for potential buyers or prospective buyers.Scenario: How a Small Mistake Can Affect Your Business SaleConsider the story of a local business owner who rushed through a business sale without a thorough business valuation or the right legal documents. What seemed like a promising sale ended with unexpected legal trouble and a lower-than-expected sale price. It’s common: small business owners may overlook cash flow patterns, misunderstand tax implications, or fail to assemble the proper agreements, all of which can stall or sink a business for sale deal. A single overlooked detail—like not reviewing your financial statements or skipping professional help from a business broker—can impact the process of selling and even cause the sale to fall through. Learning from these scenarios prepares you for a smooth and profitable sale process.What You'll Learn About Selling Your Business?The essential steps in selling your business?Common mistakes business owners makeOverview of small business and selling a small business best practicesNavigating business valuation and tax implicationsUnderstanding the Basics of Selling Your Business?Selling a business isn’t as simple as posting an ad online—it’s a process that requires clarity, documentation, and planning. Whether you’re looking to retire, pursue a new venture, or capitalize on your small business’s value, understanding the process of selling is essential. You’ll need to evaluate your readiness as a business owner, get your business valuation in order, and anticipate questions that potential buyers might ask about cash flow and the company’s financial health. Failing to prepare to sell can lead to delays, negotiation challenges, or a disappointing deal.By knowing when and how to start the sale process, you safeguard your interests and increase the likelihood of a successful business sale. Start by reviewing your financial statements and organizing all necessary legal documents. As you move forward, a good support number—whether a law firm, accountant, or professional business broker—can help guide you. Always consider your goal: whether it’s maximizing sale price, protecting your staff, or ensuring a smooth transition, planning is key in selling a small business.Who Should Consider Selling a Small Business?Not every business owner will sell, but those who do usually share common goals—retirement, relocation, or simply pursuing a new challenge. If you’re a small business owner ready to sell your business, ask yourself: Is the business profitable? Are your books and records up to date? Do you know how your company stacks up against others in the industry? Business sales are best considered when your business is in good financial shape, with clear cash flow patterns and a steady customer base. If your small business relies mostly on you, you may also need to plan for a smooth handover with potential buyers.Owners who lack an exit strategy or are caught off-guard by life’s surprises may be forced into a rushed sale, which can lead to leaving money on the table. Instead, take the time to understand your unique selling points and what prospective buyers are likely looking for. Partnering with a trusted law firm, using customer support wisely, and consulting with financial advisors can increase both sale value and the likelihood of a successful transaction.Preparing Your Small Business for SalePreparation is the foundation of a strong business sale. Start by reviewing all financial statements—potential buyers will scrutinize your revenue, expenses, and cash flow. Clean up your books, resolve any outstanding debts, and make sure inventory is organized. Good documentation makes the due diligence process—where buyers look closely at your business—smoother and faster. It also reassures prospective buyers that your business is well-managed and transparent.Next, consider your physical and digital assets. Are your facilities well-maintained? Are all licenses, permits, and insurance policies up to date? Guarantee the transfer of critical business functions won’t be disrupted. Lastly, ensure employees and key staff are aware of the transition if appropriate, and establish confidentiality by using well-crafted legal documents. A professional business broker can walk you through each step, reducing stress and keeping the process of selling clear and orderly.Determining When to Sell Your Business?Timing is everything in selling a small business. Some business owners wait for peak profitability, while others sell during a strong market or when a personal milestone approaches. The best moment to sell your business is when it’s attractive to buyers—solid financial performance, growth potential, and minimized risks will reassure any prospective buyer. However, waiting too long can hurt your chances, especially if sales or cash flow start declining.The economy, seasonal trends, and even shifts within your industry can influence the outcome of a business sale. Always be realistic—if you’re burned out, losing passion, or eager to move on, waiting for the “perfect” time can sometimes work against you. Develop an exit strategy early and consult with a business broker or law firm to determine the best selling window for you. Prioritizing your business valuation and market trends ensures you don’t miss a golden opportunity for the sale of your business.Key Steps in Selling a Small BusinessConducting a business valuationAssembling necessary legal documents for selling a businessAssessing tax implicationsCreating a strategy for selling your business?Using a trusted business brokerBusiness Valuation: How Much Is Your Business Worth?Your business valuation sets the foundation for your sale price and negotiations with potential buyers. The process typically starts by reviewing financial statements, considering both tangible and intangible assets, and benchmarking against similar businesses. A clear understanding of what your business is worth helps set realistic expectations—overvaluing may scare away buyers, while undervaluing can leave money on the table. Business brokers and accountants have experience using proven methods that maximize your sale value and demonstrate transparency for potential buyers. Always choose a method that reflects your small business’s strengths while accounting for industry standards and current market demand.Business valuation isn’t just about earnings; it includes reviewing your company’s assets, comparing recent business sales within your industry, and projecting cash flow for the prospective buyer’s benefit. The sale price will also depend on the perceived stability and growth opportunities of your business. By understanding these factors and keeping records organized, you’ll be able to confidently defend your valuation to prospective buyers and support any negotiations that arise during the sale process.Factors Affecting Business Valuation When Selling a Small BusinessSeveral factors come into play when determining your business valuation. First, the strength and consistency of cash flow carry huge weight. Businesses with predictable revenue and steady growth fetch higher value. Next, look at physical and intellectual property assets—real estate, patents, proprietary systems, and even loyal customer contracts can significantly increase your business’s appeal to potential buyers. Market conditions also impact your valuation; a healthy economy and active market in your industry can boost what your business is worth.Other key factors include operational efficiency, staff stability, and the share of revenue tied to repeat business. If your business can run smoothly without your constant involvement, buyers view it as a safer investment. Finally, any legal or operational risks—like lawsuits or unsettled debts—can lower your sale price. Address these issues early to maximize the value of your small business when selling your business?.Methods Used to Value a Business for SaleThere are multiple methods for business valuation. The three most commonly used in selling a small business are:Earnings Multiplier: This approach bases your value on a multiple of earnings, such as EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization). For service businesses or those with solid profits, this is often preferred.Asset-Based Approach: This method values your business based on the value of its tangible and intangible assets. It’s popular for businesses with significant inventory, equipment, or intellectual property.Market Comparison: Here, your business is compared to similar companies recently sold in the same industry and region. This method is useful for aligning with real-world sale prices and market trends.Valuation MethodBest ForDescriptionEarnings MultiplierProfitable businessesApplies a multiplier to annual earnings (EBITDA) to estimate a sale price.Asset-BasedAsset-heavy businessesValues assets and subtracts liabilities for total business value.Market ComparisonSimilar businesses have been sold recentlyBenchmarks business against sale prices of similar businesses.Legal Documents You Need When Selling Your Business?Having the right legal documents in place is crucial for a successful business sale. Not only do they protect both the business owner and buyer, but they also clarify expectations and help prevent disputes after the sale process is completed. A law firm specializing in business sales can help you draft these documents to ensure your interests are protected. Skipping this step can expose small business owners to risks that might jeopardize the entire transaction.Ensure all agreements are clearly outlined, signed, and stored securely. Critical legal documents not only comply with local laws but also help define the sale structure, timeline, and any warranties or non-compete terms. Proper preparation here is one of the surest ways to safeguard your interests and reassure your buyer that your business is a solid investment.Essential Agreements for Business OwnersLetter of intentSale agreementNon-disclosure agreementWorking With a Business Broker for a Smooth Business SaleFor many business owners, hiring a business broker can simplify the selling process. Brokers assess the current market, help prepare to sell, find prospective buyers, and guide negotiations. They work alongside your legal and financial support, connecting you with trusted law firms when needed. A business broker acts as an intermediary, ensuring both sellers and buyers are properly represented—reducing miscommunication, legal missteps, and emotional stress.Choose a business broker with a strong track record in selling a small business, especially in your particular industry. Their knowledge of business sales, valuation, and buyer networks can be invaluable. While there are fees associated with brokers, their ability to attract qualified buyers and secure higher sale prices often more than justifies the cost. Remember: choose your broker carefully, as the wrong one could delay your sale or undervalue your business.Tax Implications of Selling a Small BusinessUnderstanding the tax implications of a business sale can have a major impact on what you keep after closing. Depending on your business structure, the sale of your business may be taxed as ordinary income or as capital gains. If you’re selling assets versus shares, it will affect how the proceeds are taxed—making it essential to work with an accountant or tax advisor who understands business sales.Tax planning can help reduce unnecessary burdens. Simple actions like structuring the sale for maximum long-term capital gains treatment, allocating sale price components wisely, and considering installment sales can increase your after-tax proceeds. Always discuss your plans with a knowledgeable tax professional before finalizing your business sale, as mistakes here can be costly and irreversible.Capital Gains and Tax Considerations for Business OwnersWhen you sell your business, the profit is typically subject to capital gains tax. The amount you owe depends on the length of ownership, the value of your assets, and the structure of your sale agreement. Short-term gains (owned less than a year) are usually taxed at a higher rate than long-term gains. Allocating the sale price between tangible assets and goodwill can further impact your tax bill—another area where professional advice is key.Failing to plan for taxes can turn what should be a rewarding business sale into an expensive lesson. Proactive business owners examine several tax strategies to reduce their liability, and timing of the sale can sometimes make a difference in which tax year income is reported. The advice of an experienced accountant early in the process of selling your business is invaluable.Strategies to Minimize Tax Impact When You Sell Your BusinessStart early by consulting with a tax advisor to evaluate your best options. Consider using an installment sale (where payments are received over time), which allows taxes to be paid as proceeds are received, rather than all at once. Maximizing long-term capital gains treatment, where possible, can also decrease your tax bill dramatically. Structuring your legal documents clearly is essential, as is understanding any unique tax breaks specific to small business sales. These steps can help you keep more of your hard-earned sale price while staying compliant with tax laws."Proper preparation can make the difference between a smooth sale and unexpected setbacks for any business owner." — Expert Business BrokerAvoiding Common Mistakes When Selling Your Business?Not obtaining a professional business valuationInadequate legal documentsMisunderstanding tax implicationsChoosing the wrong business brokerNot preparing your small business adequatelyChecklist for Business Owners: Are You Ready to Sell Your Business?Review business valuationPrepare all legal documentsConsult with a business brokerUnderstand the tax implicationsPlan your exit timelineHow to Find the Right Buyer for Your Small BusinessFinding the right buyer is about more than just accepting the first offer. Start by identifying your ideal buyer—someone with the experience, resources, and vision to take your business forward. List your business on relevant online marketplaces, industry-specific forums, and through your business broker's network. Vet all potential buyers carefully: check for financing, experience in your sector, and a genuine interest in your business’s continued success. The better you vet, the smoother the transition for both you and your employees.Reputable business brokers often have established pipelines of qualified buyers ready for the right opportunity. By tapping into these networks—and being honest and transparent throughout negotiations—you can land a successful sale and give your business the best chance for continued growth. Remember: after all your hard work building your business, you want to pass it to someone who will treat it with the same care and attention.Where to List Your Business for SalePopular online platforms, local business associations, and professional business broker listings are all smart places to start. Get your business for sale in front of the widest pool of prospective buyers without exposing sensitive information publicly—always use a non-disclosure agreement and ask credible questions to weed out tire kickers from serious buyers. Maintaining confidentiality and working with an expert ensures your business’s reputation and staff remain protected during the sale process.Using Business Brokers to Locate BuyersMost business owners find the right buyer faster with the help of an experienced broker. These professionals advertise your business, screen prospects, and handle the tougher parts of negotiation. Their connections within the industry and knowledge of potential buyers’ qualifications make the selling process smoother and less risky for you—the business owner. Choose a broker who specializes in your type of small business for the best results.People Also AskHow much is a business worth with $500,000 in sales?A business with $500,000 in sales is typically valued using methods that consider profits, assets, and industry standards. Earnings and market comparisons are crucial when selling your business?.What is the first step to selling a business?The first step to selling your business? is preparing financial records and getting a professional business valuation.How much do you typically sell a business for?Businesses often sell for a multiple of earnings or revenue, but amounts vary based on business size, profitability, and market factors in selling your business?.What is the best way to sell my business?The best way to sell your business? is to plan early, work with professional advisors, and target the right buyers through proper listings and a reputable business broker.Frequently Asked Questions About Selling Your Business?How do I know if the timing is right for selling my business?What are the necessary legal documents?Should I hire a business broker?What are common tax considerations?Key Takeaways for Business Owners from Selling a Small BusinessThorough preparation of legal documents and understanding tax implications are essential when selling your business?Professional business valuation can maximize sale valueChoosing experienced business brokers can ease the selling a small business processFind the Expert Help You Need When Selling Your Business?Give us a call @ 1.877.776.6829 or visit our website Conciergetax.vip todayConclusion: Clear planning, expert support, and practical steps help ensure you avoid costly mistakes when selling your business. Don’t go it alone—plan, prepare, and get the right advice.

Contact:

T: +1 833 229 5500

Email: connect@keithstoller.com

About Us:

Keith Stoller coaches businesses for quick breakthroughs that foster long-lasting success.

© 2026 Stoller Companies LLC All Rights Reserved. 9350 Wilshire Blvd, Suite 203-E81 , Beverly Hills , CA 90212. Contact Us. Terms of Service . Privacy Policy

ewogICJjb21wYW55IjogIltDb21wYW55IE5hbWVdIiwKICAiYWRkcmVzcyI6ICJbQ29tcGFueSBBZGRyZXNzXSIsCiAgImNpdHkiOiAiW0NvbXBhbnkgQ2l0eV0iLAogICJzdGF0ZSI6ICJbQ29tcGFueSBTdGF0ZV0iLAogICJ6aXAiOiAiW1Bvc3RhbCBDb2RlXSIsCiAgImVtYWlsIjogIltDb21wYW55IEVtYWlsXSIsCiAgInRvcyI6ICJDanh3UGp4emRISnZibWMrUEdWdFBsZG9aVzRnZVc5MUlITnBaMjR0YVc0Z2QybDBhQ0IxY3l3Z2VXOTFJR0Z5WlNCbmFYWnBibWNtYm1KemNEc2dlVzkxY2lCd1pYSnRhWE56YVc5dUlHRnVaQ0JqYjI1elpXNTBJSFJ2SUhObGJtUWdlVzkxSUdWdFlXbHNJR0Z1WkM5dmNpQlRUVk1nZEdWNGRDQnRaWE56WVdkbGN5NGdRbmtnWTJobFkydHBibWNnZEdobElGUmxjbTF6SUdGdVpDQkRiMjVrYVhScGIyNXpJR0p2ZUNCaGJtUWdZbmtnYzJsbmJtbHVaeUJwYmlCNWIzVWdZWFYwYjIxaGRHbGpZV3hzZVNCamIyNW1hWEp0SUhSb1lYUWdlVzkxSUdGalkyVndkQ0JoYkd3Z2RHVnliWE1nYVc0Z2RHaHBjeUJoWjNKbFpXMWxiblF1UEM5bGJUNDhMM04wY205dVp6NDhMM0ErQ2p4d1BpWnVZbk53T3p3dmNENEtQSEErUEhOMGNtOXVaejVUUlZKV1NVTkZQQzl6ZEhKdmJtYytQQzl3UGdvOGNENVhaU0J3Y205MmFXUmxJR0VnYzJWeWRtbGpaU0IwYUdGMElHTjFjbkpsYm5Sc2VTQmhiR3h2ZDNNZ2VXOTFJSFJ2SUhKbFkyVnBkbVVnY21WeGRXVnpkSE1nWm05eUlHWmxaV1JpWVdOckxDQmpiMjF3WVc1NUlHbHVabTl5YldGMGFXOXVMQ0J3Y205dGIzUnBiMjVoYkNCcGJtWnZjbTFoZEdsdmJpd2dZMjl0Y0dGdWVTQmhiR1Z5ZEhNc0lHTnZkWEJ2Ym5Nc0lHUnBjMk52ZFc1MGN5QmhibVFnYjNSb1pYSWdibTkwYVdacFkyRjBhVzl1Y3lCMGJ5QjViM1Z5SUdWdFlXbHNJR0ZrWkhKbGMzTWdZVzVrTDI5eUlHTmxiR3gxYkdGeUlIQm9iMjVsSUc5eUlHUmxkbWxqWlM0Z1dXOTFJSFZ1WkdWeWMzUmhibVFnWVc1a0lHRm5jbVZsSUhSb1lYUWdkR2hsSUZObGNuWnBZMlVnYVhNZ2NISnZkbWxrWldRZ0puRjFiM1E3UVZNdFNWTW1jWFZ2ZERzZ1lXNWtJSFJvWVhRZ2QyVWdZWE56ZFcxbElHNXZJSEpsYzNCdmJuTnBZbWxzYVhSNUlHWnZjaUIwYUdVZ2RHbHRaV3hwYm1WemN5d2daR1ZzWlhScGIyNHNJRzFwY3kxa1pXeHBkbVZ5ZVNCdmNpQm1ZV2xzZFhKbElIUnZJSE4wYjNKbElHRnVlU0IxYzJWeUlHTnZiVzExYm1sallYUnBiMjV6SUc5eUlIQmxjbk52Ym1Gc2FYcGhkR2x2YmlCelpYUjBhVzVuY3k0OEwzQStDanh3UGxsdmRTQmhjbVVnY21WemNHOXVjMmxpYkdVZ1ptOXlJRzlpZEdGcGJtbHVaeUJoWTJObGMzTWdkRzhnZEdobElGTmxjblpwWTJVZ1lXNWtJSFJvWVhRZ1lXTmpaWE56SUcxaGVTQnBiblp2YkhabElIUm9hWEprSUhCaGNuUjVJR1psWlhNZ0tITjFZMmdnWVhNZ1UwMVRJSFJsZUhRZ2JXVnpjMkZuWlhNc0lFbHVkR1Z5Ym1WMElITmxjblpwWTJVZ2NISnZkbWxrWlhJZ2IzSWdZMlZzYkhWc1lYSWdZV2x5ZEdsdFpTQmphR0Z5WjJWektTNGdXVzkxSUdGeVpTQnlaWE53YjI1emFXSnNaU0JtYjNJZ2RHaHZjMlVnWm1WbGN5d2dhVzVqYkhWa2FXNW5JSFJvYjNObElHWmxaWE1nWVhOemIyTnBZWFJsWkNCM2FYUm9JSFJvWlNCa2FYTndiR0Y1SUc5eUlHUmxiR2wyWlhKNUlHOW1JR1ZoWTJnZ1UwMVRJSFJsZUhRZ2JXVnpjMkZuWlNCelpXNTBJSFJ2SUhsdmRTQmllU0IxY3k0Z1NXNGdZV1JrYVhScGIyNHNJSGx2ZFNCdGRYTjBJSEJ5YjNacFpHVWdZVzVrSUdGeVpTQnlaWE53YjI1emFXSnNaU0JtYjNJZ1lXeHNJR1Z4ZFdsd2JXVnVkQ0J1WldObGMzTmhjbmtnZEc4Z1lXTmpaWE56SUhSb1pTQlRaWEoyYVdObElHRnVaQ0J5WldObGFYWmxJSFJvWlNCVFRWTWdkR1Y0ZENCdFpYTnpZV2RsY3k0Z1YyVWdaRzhnYm05MElHTm9ZWEpuWlNCaGJua2dabVZsY3lCbWIzSWdaR1ZzYVhabGNua2diMllnWlcxaGFXd2diM0lnVTAxVExpQlVhR2x6SUdseklHRWdabkpsWlNCelpYSjJhV05sSUhCeWIzWnBaR1ZrSUdKNUlIVnpMaUJJYjNkbGRtVnlMQ0J3YkdWaGMyVWdZMmhsWTJzZ2QybDBhQ0I1YjNWeUlHbHVkR1Z5Ym1WMElITmxjblpwWTJVZ2NISnZkbWxrWlhJZ1lXNWtJR05sYkd4MWJHRnlJR05oY25KcFpYSWdabTl5SUdGdWVTQmphR0Z5WjJWeklIUm9ZWFFnYldGNUlHbHVZM1Z5SUdGeklHRWdjbVZ6ZFd4MElHWnliMjBnY21WalpXbDJhVzVuSUdWdFlXbHNJR0Z1WkNCVFRWTWdkR1Y0ZENCdFpYTnpZV2RsY3lCMGFHRjBJSGRsSUdSbGJHbDJaWElnZFhCdmJpQjViM1Z5SUc5d2RDMXBiaUJoYm1RZ2NtVm5hWE4wY21GMGFXOXVJSGRwZEdnZ2IzVnlJR1Z0WVdsc0lHRnVaQ0JUVFZNZ2MyVnlkbWxqWlhNdUlGbHZkU0JqWVc0Z1kyRnVZMlZzSUdGMElHRnVlU0IwYVcxbExpQktkWE4wSUhSbGVIUWdKbkYxYjNRN1UxUlBVQ1p4ZFc5ME95QjBieVp1WW5Od096eG9hV2RvYkdsbmFIUWdZMnhoYzNNOUltTnZiWEJoYm5sVFRWTlFhRzl1WlZWd1pHRjBaU0krUEM5b2FXZG9iR2xuYUhRK0xpQkJablJsY2lCNWIzVWdjMlZ1WkNCMGFHVWdVMDFUSUcxbGMzTmhaMlVnSm5GMWIzUTdVMVJQVUNaeGRXOTBPeUIwYnlCMWN5d2dkMlVnZDJsc2JDQnpaVzVrSUhsdmRTQmhiaUJUVFZNZ2JXVnpjMkZuWlNCMGJ5QmpiMjVtYVhKdElIUm9ZWFFnZVc5MUlHaGhkbVVnWW1WbGJpQjFibk4xWW5OamNtbGlaV1F1SUVGbWRHVnlJSFJvYVhNc0lIbHZkU0IzYVd4c0lHNXZJR3h2Ym1kbGNpQnlaV05sYVhabElGTk5VeUJ0WlhOellXZGxjeUJtY205dElIVnpMand2Y0Q0S1BIQStQSE4wY205dVp6NVpUMVZTSUZKRlIwbFRWRkpCVkVsUFRpQlBRa3hKUjBGVVNVOU9Vend2YzNSeWIyNW5Qand2Y0Q0S1BIQStTVzRnWTI5dWMybGtaWEpoZEdsdmJpQnZaaUI1YjNWeUlIVnpaU0J2WmlCMGFHVWdVMlZ5ZG1salpTd2dlVzkxSUdGbmNtVmxJSFJ2T2p3dmNENEtQRzlzUGdvZ0lDQWdQR3hwUG5CeWIzWnBaR1VnZEhKMVpTd2dZV05qZFhKaGRHVXNJR04xY25KbGJuUWdZVzVrSUdOdmJYQnNaWFJsSUdsdVptOXliV0YwYVc5dUlHRmliM1YwSUhsdmRYSnpaV3htSUdGeklIQnliMjF3ZEdWa0lHSjVJSFJvWlNCVFpYSjJhV05sSmlNek9UdHpJSEpsWjJsemRISmhkR2x2YmlCbWIzSnRJQ2h6ZFdOb0lHbHVabTl5YldGMGFXOXVJR0psYVc1bklIUm9aU0FtY1hWdmREdFNaV2RwYzNSeVlYUnBiMjRnUkdGMFlTWnhkVzkwT3lrZ1lXNWtQQzlzYVQ0S0lDQWdJRHhzYVQ1dFlXbHVkR0ZwYmlCaGJtUWdjSEp2YlhCMGJIa2dkWEJrWVhSbElIUm9aU0JTWldkcGMzUnlZWFJwYjI0Z1JHRjBZU0IwYnlCclpXVndJR2wwSUhSeWRXVXNJR0ZqWTNWeVlYUmxMQ0JqZFhKeVpXNTBJR0Z1WkNCamIyMXdiR1YwWlM0Z1NXWWdlVzkxSUhCeWIzWnBaR1VnWVc1NUlHbHVabTl5YldGMGFXOXVJSFJvWVhRZ2FYTWdkVzUwY25WbExDQnBibUZqWTNWeVlYUmxMQ0J1YjNRZ1kzVnljbVZ1ZENCdmNpQnBibU52YlhCc1pYUmxMQ0J2Y2lCM1pTQm9ZWFpsSUhKbFlYTnZibUZpYkdVZ1ozSnZkVzVrY3lCMGJ5QnpkWE53WldOMElIUm9ZWFFnYzNWamFDQnBibVp2Y20xaGRHbHZiaUJwY3lCMWJuUnlkV1VzSUdsdVlXTmpkWEpoZEdVc0lHNXZkQ0JqZFhKeVpXNTBJRzl5SUdsdVkyOXRjR3hsZEdVc0lIZGxJR2hoZG1VZ2RHaGxJSEpwWjJoMElIUnZJSE4xYzNCbGJtUWdiM0lnUEhOMGNtOXVaejQ4YzNCaGJpQnpkSGxzWlQwaVkyOXNiM0k2STBaR01EQXdNRHNpUG5SbGNtMXBibUYwWlNCNWIzVnlJR0ZqWTI5MWJuUXZjSEp2Wm1sc1pTQmhibVFnY21WbWRYTmxJR0Z1ZVNCaGJtUWdZV3hzSUdOMWNuSmxiblFnYjNJZ1puVjBkWEpsSUhWelpTQnZaaUIwYUdVZ1UyVnlkbWxqWlNBb2IzSWdZVzU1SUhCdmNuUnBiMjRnZEdobGNtVnZaaWt1UEM5emNHRnVQand2YzNSeWIyNW5Qand2YkdrK0Nqd3ZiMncrQ2p4d1BpWnVZbk53T3p3dmNENEtQR2hwWjJoc2FXZG9kQ0JqYkdGemN6MGlZMjl0Y0dGdWVVNWhiV1ZWY0dSaGRHVWlQbHREYjIxd1lXNTVJRTVoYldWZFBDOW9hV2RvYkdsbmFIUStQR0p5SUM4K0NqeG9hV2RvYkdsbmFIUWdZMnhoYzNNOUltTnZiWEJoYm5sQlpHUnlaWE56VlhCa1lYUmxJajViUTI5dGNHRnVlU0JCWkdSeVpYTnpYVHd2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ284YUdsbmFHeHBaMmgwSUdOc1lYTnpQU0pqYjIxd1lXNTVVR2h2Ym1WVmNHUmhkR1VpUGx0RGIyMXdZVzU1SUZCb2IyNWxYVHd2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ284YUdsbmFHeHBaMmgwSUdOc1lYTnpQU0pqYjIxd1lXNTVSVzFoYVd4VmNHUmhkR1VpUGx0RGIyMXdZVzU1SUVWdFlXbHNYVHd2YUdsbmFHeHBaMmgwUGp4aWNpQXZQZ289IiwKICAicHJpdmFjeSI6ICJDanh3UGp4emRISnZibWMrVUZKSlZrRkRXVHd2YzNSeWIyNW5Qand2Y0Q0S1BIQStQSE4wY205dVp6NVVhR1VnYVc1bWIzSnRZWFJwYjI0Z2NISnZkbWxrWldRZ1pIVnlhVzVuSUhSb2FYTWdjbVZuYVhOMGNtRjBhVzl1SUdseklHdGxjSFFnY0hKcGRtRjBaU0JoYm1RZ1kyOXVabWxrWlc1MGFXRnNMQ0JoYm1RZ2QybHNiQ0J1WlhabGNpQmlaU0JrYVhOMGNtbGlkWFJsWkN3Z1kyOXdhV1ZrTENCemIyeGtMQ0IwY21Ga1pXUWdiM0lnY0c5emRHVmtJR2x1SUdGdWVTQjNZWGtzSUhOb1lYQmxJRzl5SUdadmNtMHVJRlJvYVhNZ2FYTWdiM1Z5SUdkMVlYSmhiblJsWlM0OEwzTjBjbTl1Wno0OEwzQStDanh3UGp4emRISnZibWMrU1U1RVJVMU9TVlJaUEM5emRISnZibWMrUEM5d1BnbzhjRDQ4WlcwK1dXOTFJR0ZuY21WbElIUnZJR2x1WkdWdGJtbG1lU0JoYm1RZ2FHOXNaQ0IxY3l3dUlHRnVaQ0JwZEhNZ2MzVmljMmxrYVdGeWFXVnpMQ0JoWm1acGJHbGhkR1Z6TENCdlptWnBZMlZ5Y3l3Z1lXZGxiblJ6TENCamJ5MWljbUZ1WkdWeWN5QnZjaUJ2ZEdobGNpQndZWEowYm1WeWN5d2dZVzVrSUdWdGNHeHZlV1ZsY3l3Z2FHRnliV3hsYzNNZ1puSnZiU0JoYm5rZ1kyeGhhVzBnYjNJZ1pHVnRZVzVrTENCcGJtTnNkV1JwYm1jZ2NtVmhjMjl1WVdKc1pTQmhkSFJ2Y201bGVYTW1Jek01T3lCbVpXVnpMQ0J0WVdSbElHSjVJR0Z1ZVNCMGFHbHlaQ0J3WVhKMGVTQmtkV1VnZEc4Z2IzSWdZWEpwYzJsdVp5QnZkWFFnYjJZZ1EyOXVkR1Z1ZENCNWIzVWdjbVZqWldsMlpTd2djM1ZpYldsMExDQnlaWEJzZVN3Z2NHOXpkQ3dnZEhKaGJuTnRhWFFnYjNJZ2JXRnJaU0JoZG1GcGJHRmliR1VnZEdoeWIzVm5hQ0IwYUdVZ1UyVnlkbWxqWlN3Z2VXOTFjaUIxYzJVZ2IyWWdkR2hsSUZObGNuWnBZMlVzSUhsdmRYSWdZMjl1Ym1WamRHbHZiaUIwYnlCMGFHVWdVMlZ5ZG1salpTd2dlVzkxY2lCMmFXOXNZWFJwYjI0Z2IyWWdkR2hsSUZSUFV5d2diM0lnZVc5MWNpQjJhVzlzWVhScGIyNGdiMllnWVc1NUlISnBaMmgwY3lCdlppQmhibTkwYUdWeUxqd3ZaVzArUEM5d1BnbzhjRDQ4YzNSeWIyNW5Qa1JKVTBOTVFVbE5SVklnVDBZZ1YwRlNVa0ZPVkVsRlV6d3ZjM1J5YjI1blBqd3ZjRDRLUEhBK1BITjBjbTl1Wno1WlQxVWdSVmhRVWtWVFUweFpJRlZPUkVWU1UxUkJUa1FnUVU1RUlFRkhVa1ZGSUZSSVFWUTZQQzl6ZEhKdmJtYytQQzl3UGdvOGIydytDZ2s4YkdrK1dVOVZVaUJWVTBVZ1QwWWdWRWhGSUZORlVsWkpRMFVnU1ZNZ1FWUWdXVTlWVWlCVFQweEZJRkpKVTBzdUlGUklSU0JUUlZKV1NVTkZJRWxUSUZCU1QxWkpSRVZFSUU5T0lFRk9JQ1p4ZFc5ME8wRlRJRWxUSm5GMWIzUTdJRUZPUkNBbWNYVnZkRHRCVXlCQlZrRkpURUZDVEVVbWNYVnZkRHNnUWtGVFNWTXVJQ3d1SUVGT1JDQlZVeXdnU1ZRbUl6TTVPMU1nUTFWVFZFOU5SVkpUTENCRldGQlNSVk5UVEZrZ1JFbFRRMHhCU1UxVElFRk1UQ0JYUVZKU1FVNVVTVVZUSUU5R0lFRk9XU0JMU1U1RUxDQlhTRVZVU0VWU0lFVllVRkpGVTFNZ1QxSWdTVTFRVEVsRlJDd2dTVTVEVEZWRVNVNUhMQ0JDVlZRZ1RrOVVJRXhKVFVsVVJVUWdWRThnVkVoRklFbE5VRXhKUlVRZ1YwRlNVa0ZPVkVsRlV5QlBSaUJOUlZKRFNFRk9WRUZDU1V4SlZGa3NJRVpKVkU1RlUxTWdSazlTSUVFZ1VFRlNWRWxEVlV4QlVpQlFWVkpRVDFORklFRk9SQ0JPVDA0dFNVNUdVa2xPUjBWTlJVNVVMand2YkdrK0NnazhiR2srVFVGTFJWTWdUazhnVjBGU1VrRk9WRmtnVkVoQlZDQW9hU2tnVkVoRklGTkZVbFpKUTBVZ1YwbE1UQ0JOUlVWVUlGbFBWVklnVWtWUlZVbFNSVTFGVGxSVExDQW9hV2twSUZSSVJTQlRSVkpXU1VORklGZEpURXdnUWtVZ1ZVNUpUbFJGVWxKVlVGUkZSQ3dnVkVsTlJVeFpMQ0JUUlVOVlVrVXNJRTlTSUVWU1VrOVNMVVpTUlVVc0lDaHBhV2twSUZSSVJTQlNSVk5WVEZSVElGUklRVlFnVFVGWklFSkZJRTlDVkVGSlRrVkVJRVpTVDAwZ1ZFaEZJRlZUUlNCUFJpQlVTRVVnVTBWU1ZrbERSU0JYU1V4TUlFSkZJRUZEUTFWU1FWUkZJRTlTSUZKRlRFbEJRa3hGTENCQlRrUWdLR2wyS1NCQlRsa2dSVkpTVDFKVElFbE9JRlJJUlNCVFQwWlVWMEZTUlNCWFNVeE1JRUpGSUVOUFVsSkZRMVJGUkM0OEwyeHBQZ29KUEd4cFBrRk9XU0JOUVZSRlVrbEJUQ0JFVDFkT1RFOUJSRVZFSUU5U0lFOVVTRVZTVjBsVFJTQlBRbFJCU1U1RlJDQlVTRkpQVlVkSUlGUklSU0JWVTBVZ1QwWWdWRWhGSUZORlVsWkpRMFVnU1ZNZ1JFOU9SU0JCVkNCWlQxVlNJRTlYVGlCRVNWTkRVa1ZVU1U5T0lFRk9SQ0JTU1ZOTElFRk9SQ0JVU0VGVUlGbFBWU0JYU1V4TUlFSkZJRk5QVEVWTVdTQlNSVk5RVDA1VFNVSk1SU0JHVDFJZ1FVNVpJRVJCVFVGSFJTQlVUeUJaVDFWU0lFTlBUVkJWVkVWU0lGTlpVMVJGVFNCUFVpQk1UMU5USUU5R0lFUkJWRUVnVkVoQlZDQlNSVk5WVEZSVElFWlNUMDBnVkVoRklFUlBWMDVNVDBGRUlFOUdJRUZPV1NCVFZVTklJRTFCVkVWU1NVRk1Mand2YkdrK0NnazhiR2srVGs4Z1FVUldTVU5GSUU5U0lFbE9SazlTVFVGVVNVOU9MQ0JYU0VWVVNFVlNJRTlTUVV3Z1QxSWdWMUpKVkZSRlRpd2dUMEpVUVVsT1JVUWdRbGtnV1U5VklFWlNUMDBnVDFJZ1ZFaFNUMVZIU0NCUFVpQkdVazlOSUZSSVJTQlRSVkpXU1VORklGTklRVXhNSUVOU1JVRlVSU0JCVGxrZ1YwRlNVa0ZPVkZrZ1RrOVVJRVZZVUZKRlUxTk1XU0JUVkVGVVJVUWdTVTRnVkVoRklGUlBVeTQ4TDJ4cFBnbzhMMjlzUGdvOGNENDhjM1J5YjI1blBreEpUVWxVUVZSSlQwNGdUMFlnVEVsQlFrbE1TVlJaUEM5emRISnZibWMrUEM5d1BnbzhjRDVaVDFVZ1JWaFFVa1ZUVTB4WklGVk9SRVZTVTFSQlRrUWdRVTVFSUVGSFVrVkZJRlJJUVZRZ1FVNUVJRk5JUVV4TUlFNVBWQ0JDUlNCTVNVRkNURVVnUms5U0lFRk9XU0JFU1ZKRlExUXNJRWxPUkVsU1JVTlVMQ0JKVGtOSlJFVk9WRUZNTENCVFVFVkRTVUZNTENCRFQwNVRSVkZWUlU1VVNVRk1JRTlTSUVWWVJVMVFURUZTV1NCRVFVMUJSMFZUTENCSlRrTk1WVVJKVGtjZ1FsVlVJRTVQVkNCTVNVMUpWRVZFSUZSUExDQkVRVTFCUjBWVElFWlBVaUJNVDFOVElFOUdJRkJTVDBaSlZGTXNJRWRQVDBSWFNVeE1MQ0JWVTBVc0lFUkJWRUVnVDFJZ1QxUklSVklnU1U1VVFVNUhTVUpNUlNCTVQxTlRSVk1nS0VWV1JVNGdTVVlnU0VGVElFSkZSVTRnUVVSV1NWTkZSQ0JQUmlCVVNFVWdVRTlUVTBsQ1NVeEpWRmtnVDBZZ1UxVkRTQ0JFUVUxQlIwVlRLU3dnVWtWVFZVeFVTVTVISUVaU1QwMDZQQzl3UGdvOGIydytDZ2s4YkdrK1ZFaEZJRlZUUlNCUFVpQlVTRVVnU1U1QlFrbE1TVlJaSUZSUElGVlRSU0JVU0VVZ1UwVlNWa2xEUlRzOEwyeHBQZ29KUEd4cFBsUklSU0JEVDFOVUlFOUdJRkJTVDBOVlVrVk5SVTVVSUU5R0lGTlZRbE5VU1ZSVlZFVWdSMDlQUkZNZ1FVNUVJRk5GVWxaSlEwVlRJRkpGVTFWTVZFbE9SeUJHVWs5TklFRk9XU0JIVDA5RVV5d2dSRUZVUVN3Z1NVNUdUMUpOUVZSSlQwNGdUMUlnVTBWU1ZrbERSVk1nVUZWU1EwaEJVMFZFSUU5U0lFOUNWRUZKVGtWRUlFOVNJRTFGVTFOQlIwVlRJRkpGUTBWSlZrVkVJRTlTSUZSU1FVNVRRVU5VU1U5T1V5QkZUbFJGVWtWRUlFbE9WRThnVkVoU1QxVkhTQ0JQVWlCR1VrOU5JRlJJUlNCVFJWSldTVU5GT3p3dmJHaytDZ2s4YkdrK1ZVNUJWVlJJVDFKSldrVkVJRUZEUTBWVFV5QlVUeUJQVWlCQlRGUkZVa0ZVU1U5T0lFOUdJRmxQVlZJZ1ZGSkJUbE5OU1ZOVFNVOU9VeUJQVWlCRVFWUkJPend2YkdrK0NnazhiR2srVTFSQlZFVk5SVTVVVXlCUFVpQkRUMDVFVlVOVUlFOUdJRUZPV1NCVVNFbFNSQ0JRUVZKVVdTQlBUaUJVU0VVZ1UwVlNWa2xEUlRzZ1QxSThMMnhwUGdvSlBHeHBQa0ZPV1NCUFZFaEZVaUJOUVZSVVJWSWdVa1ZNUVZSSlRrY2dWRThnVkVoRklGTkZVbFpKUTBVdVBDOXNhVDRLUEM5dmJENEtQSEErUEhVK1Fua2djbVZuYVhOMFpYSnBibWNnWVc1a0lITjFZbk5qY21saWFXNW5JSFJ2SUc5MWNpQmxiV0ZwYkNCaGJtUWdVMDFUSUhObGNuWnBZMlVzSUdKNUlHOXdkQzFwYml3Z2IyNXNhVzVsSUhKbFoybHpkSEpoZEdsdmJpQnZjaUJpZVNCbWFXeHNhVzVuSUc5MWRDQmhJR05oY21Rc0lDWnhkVzkwTzNsdmRTQmhaM0psWlNCMGJ5QjBhR1Z6WlNCVVJWSk5VeUJQUmlCVFJWSldTVU5GSm5GMWIzUTdJR0Z1WkNCNWIzVWdZV05yYm05M2JHVmtaMlVnWVc1a0lIVnVaR1Z5YzNSaGJtUWdkR2hsSUdGaWIzWmxJSFJsY20xeklHOW1JSE5sY25acFkyVWdiM1YwYkdsdVpXUWdZVzVrSUdSbGRHRnBiR1ZrSUdadmNpQjViM1VnZEc5a1lYa3VQQzkxUGp3dmNENEtQSEErSm01aWMzQTdQQzl3UGdvOGFHbG5hR3hwWjJoMElHTnNZWE56UFNKamIyMXdZVzU1VG1GdFpWVndaR0YwWlNJK1cwTnZiWEJoYm5rZ1RtRnRaVjA4TDJocFoyaHNhV2RvZEQ0OFluSWdMejRLUEdocFoyaHNhV2RvZENCamJHRnpjejBpWTI5dGNHRnVlVUZrWkhKbGMzTlZjR1JoZEdVaVBsdERiMjF3WVc1NUlFRmtaSEpsYzNOZFBDOW9hV2RvYkdsbmFIUStQR0p5SUM4K0NqeG9hV2RvYkdsbmFIUWdZMnhoYzNNOUltTnZiWEJoYm5sUWFHOXVaVlZ3WkdGMFpTSStXME52YlhCaGJua2dVR2h2Ym1WZFBDOW9hV2RvYkdsbmFIUStQR0p5SUM4K0NqeG9hV2RvYkdsbmFIUWdZMnhoYzNNOUltTnZiWEJoYm5sRmJXRnBiRlZ3WkdGMFpTSStXME52YlhCaGJua2dSVzFoYVd4ZFBDOW9hV2RvYkdsbmFIUStQR0p5SUM4K0NnPT0iCn0=

Terms of Service

Privacy Policy

Core Modal Title

Sorry, no results found

You Might Find These Articles Interesting

T
Please Check Your Email
We Will Be Following Up Shortly
*
*
*